
Creative Financing for Multifamily Properties: The 2026 Investor Blueprint
What if the biggest obstacle to your real estate empire isn't the bank, but your own reliance on them? In 2026, traditional lending has become a maze of restrictive requirements and rising hurdles that can stall even the most ambitious portfolios. You don't need a massive pile of cash or a perfect credit score to dominate this market. By mastering creative financing for multifamily properties, you can acquire 5+ unit buildings with low money down while your competitors are still waiting for a pre-approval letter that might never come.
It's frustrating to watch prime deals slip away because of rigid bank requirements or the fear of draining your personal savings. We know the current 105% premium to buy versus rent has created a massive opportunity, but only for those who know how to structure deals differently. This guide is your elite blueprint to bypass the hurdles of the 2026 economy. You'll discover how to pitch sellers on creative terms, utilize performance-based structures, and scale your portfolio at a speed that traditional investors can't touch. Stop waiting for permission. Take control of your financial destiny and start building your legacy today.
Key Takeaways
- Discover why creative financing for multifamily properties is the primary strategic weapon to control multi-million dollar assets with the capital of a single-family home.
- Master the "Carry-Back" and Master Lease Options to turn property owners into your private bank and bypass traditional lending hurdles.
- Learn to stack capital using silent equity partners and syndication strategies to fund down payments without draining your personal accounts.
- Identify high-equity, motivated sellers and filter off-market leads instantly using proprietary software like Real Estate Radar.
- Follow a proven 90-day roadmap to secure your first apartment deal and scale your portfolio rapidly in the 2026 market.
The Power of Creative Financing: Why Apartments are Your 2026 Wealth Vehicle
Stop thinking small. In 2026, traditional bank rules are designed to keep you on the sidelines. While others struggle with restrictive lending requirements, elite investors are using creative financing for multifamily properties to control $2 million assets with the capital usually reserved for a single-family home. It's about leverage redefined. You don't need permission from a loan officer to build an empire; you need a superior strategy.
High interest rates aren't a barrier; they're a filter. They've created a massive gap between what banks will lend and what sellers expect to receive. This gap is your primary opportunity. Understanding the fundamentals of Creative Financing Techniques allows you to step in where traditional buyers fail. You aren't just buying a building. You're solving a seller's problem using sophisticated debt structures that prioritize your long-term wealth over their immediate tax liability.
To better understand how you can enter this market regardless of your current capital, watch this helpful video:
The "No Money Down" Myth vs. Reality
Forget the late-night infomercials. Serious multifamily deals rarely involve zero dollars, but they frequently involve "low money down" strategies. The psychological shift is massive. You must stop being a humble borrower and start being a strategic deal-maker. If you don't have the cash, you must bring the expertise or the structure. Trading a piece of the equity for the capital needed to close is how the pros scale without draining their personal bank accounts. It's about being the architect of the deal, not just the check writer.
Multifamily Scalability in 2026
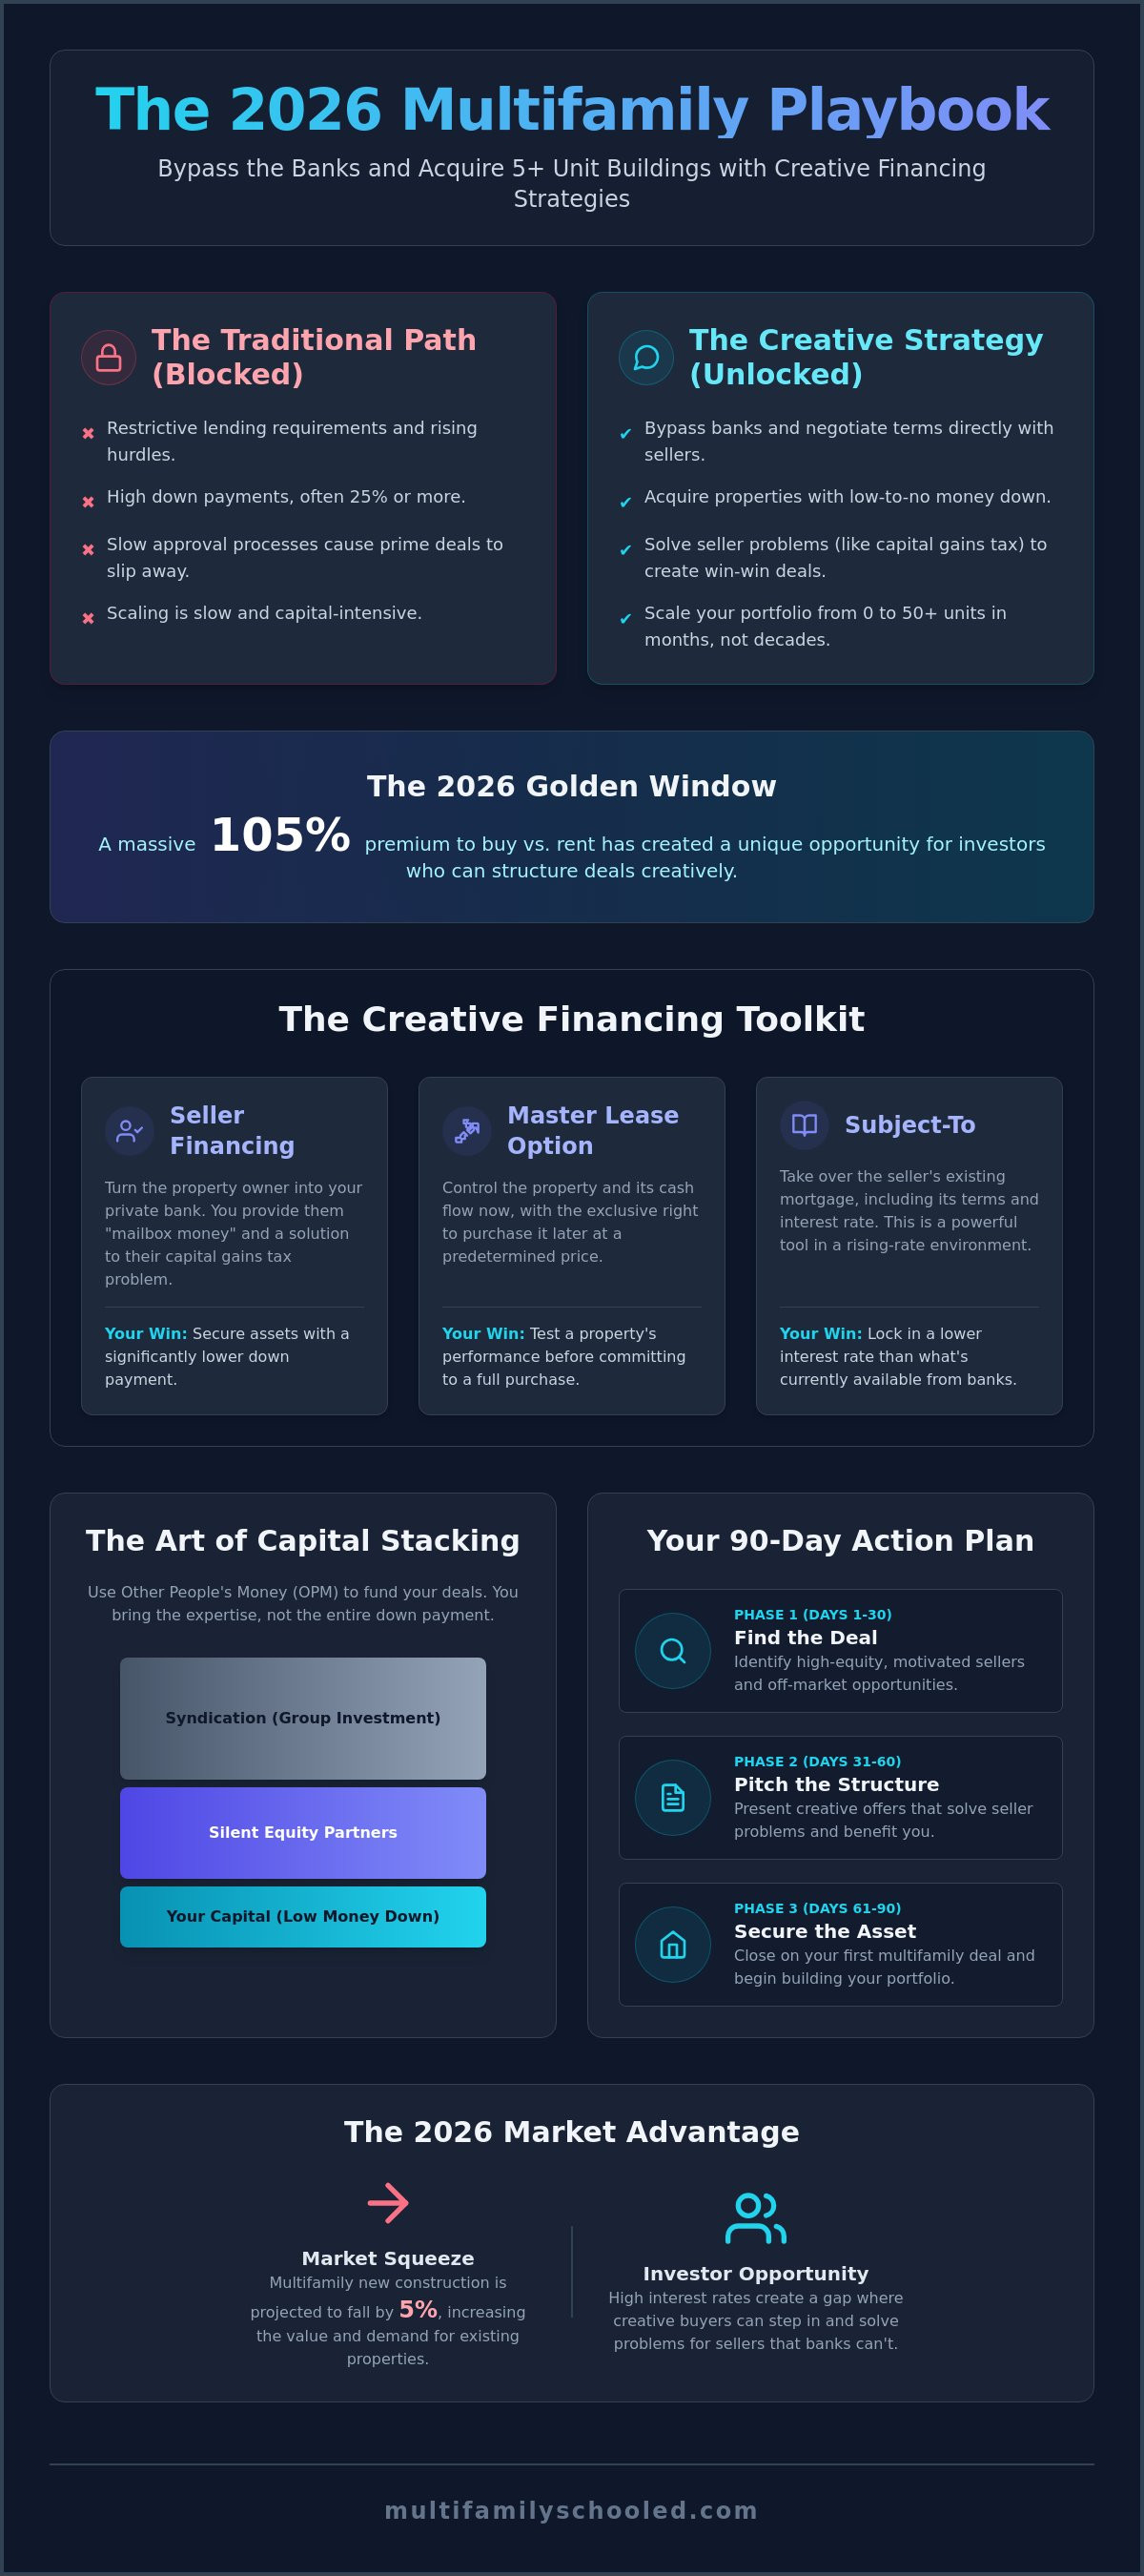
Managing one roof over fifty units is cheaper and faster than managing fifty separate houses. This is why commercial financing is the ultimate wealth vehicle. In 2026, we're seeing a "Golden Window." Multifamily starts are projected to fall 5% by the end of the year, making existing properties highly sought after. Your financing power is tied directly to Net Operating Income (NOI). When you increase the property's income, you instantly increase your equity and your ability to leverage further. Speed is everything. Tools like Real Estate Radar help you find these off-market opportunities before the rest of the market even knows they exist. By using Other People's Money (OPM), you can scale from zero to 50 units in months rather than decades.
The Creative Financing Toolkit: Seller Financing, Master Leases, and Subject-To
You need tools that banks can't touch. Creative financing for multifamily properties isn't a single trick; it's a strategic arsenal. Traditional products like Fannie Mae multifamily financing currently offer rates starting around 5.57%, but they often demand 25% down and perfect historical records. Creative tools let you bypass those gatekeepers entirely. You aren't just a buyer. You're a problem solver. You're looking for the gap between a seller's needs and the bank's rigid boxes.
Seller financing is the crown jewel of this toolkit. You turn the property owner into your private bank. They get consistent income without the headaches of property management. It's a pure financial play for them; a wealth-building play for you. By removing the institutional lender, you remove the biggest hurdle to your next 20-unit acquisition.
Mastering Seller Financing
Pitching a seller on a carry-back is about solving their tax problem. Many owners of 5-50 unit buildings have high equity and fear a massive capital gains hit upon sale. By structuring a note with specific interest rates and a 5-year balloon, you provide them with tax-deferred, steady income. This is the "Mailbox Money" pitch. You win by securing the asset with a lower down payment. They win by avoiding a massive tax bill while earning interest on their equity. It's a classic win-win scenario that traditional brokers often overlook.
Subject-To and Wraparounds offer a different path. In 2026, many properties still carry low-interest debt from previous cycles. Taking over that debt "subject-to" the existing mortgage is like walking into a pre-funded deal. A wraparound mortgage takes it further. It creates a new note that "wraps" around that original debt. You pay the seller their equity over time while keeping that low interest rate active. This preserves cash flow in a high-rate environment and makes deals work that would otherwise fail under new bank terms.
The Master Lease Strategy
The Master Lease Option (MLO) is the ultimate "test-drive" for an apartment building. You take over the management and cash flow without an immediate title transfer. Your job is to increase the Net Operating Income (NOI) by improving operations or reducing vacancies. As you improve the property, the value goes up. Because you locked in the purchase price with an "option," all that new equity belongs to you. This is a powerful way to use creative financing for multifamily properties to control large assets with minimal initial risk.
This strategy is perfect for properties that aren't currently "bankable" due to low occupancy or poor management. You fix the operations, stabilize the building, and then use that higher valuation to secure a traditional loan later to pay off the seller. It's a low-risk entry with massive upside. If you want to see these strategies in action on real deals, our Mentorship Program provides the exact scripts and structures we use to close these off-market opportunities every day.
Creative Capital Stacking: Syndication and Private Money
Don't let a 25% down payment requirement kill your momentum. In 2026, the elite game isn't about having all the cash; it's about stacking the capital. Even with community bank rates hovering around 6.1%, you still need to bridge the gap between the loan and the purchase price. This is where creative financing for multifamily properties becomes a team sport. You provide the vision. Your partners provide the fuel. You aren't just a buyer; you're a deal sponsor.
Equity partners are your silent engine. These are individuals who want the tax benefits and cash flow of real estate but don't want to manage a 20-unit building. By bringing in partners, you can cover the bank's down payment requirement while retaining control of the asset. Syndication takes this further. It's the art of pooling capital from multiple investors to take down larger assets. You act as the General Partner (GP), managing the property, while your investors act as Limited Partners (LP). It's a powerful way to scale without personal capital.
The Basics of Raising Capital
Raising money is about selling a future. You must pitch the vision of long-term stability and asset accumulation. In 2026, with the homeownership premium at 105%, apartments are a financial fortress. Investors are looking for yield. Be clear about the GP/LP split. Typically, you'll earn a percentage of the cash flow and equity for finding and managing the deal. Stay compliant. Always consult with a securities attorney to ensure you follow SEC rules for syndicators. Professionalism is your best defense against hesitation.
Hard money and private money are not the same thing. Hard money lenders are institutional. They move fast but charge higher rates, often between 9.99% and 11.00% in the current market. Private money is personal. It comes from your network. It's more flexible and often more affordable. Successful investors use "Gap" funding to layer these sources. You might secure a bank loan for 70%, a seller carry-back for 10%, and private money for the remaining 20%. That's how you close with zero personal capital. This is the ultimate leverage strategy.
Finding Private Lenders
Networking is where the hidden money lives. In 2026, capital is sitting in underperforming stocks and low-yield savings accounts. Your job is to show them a better way. You don't need a massive portfolio to start. You need a track record of competence. Use the Multifamily Tool Kit to present professional, institutional-grade numbers to your potential lenders. When you show up with a systematic plan and a proprietary methodology, the money follows. Build the system, and the capital will find you. Stop waiting for the perfect time. The perfect time is when you have the deal and the data to prove it works.
The 90-Day Deal-Finding Roadmap: Hunting for Creative Opportunities
You have the blueprint and the capital stacking strategies. Now you need the target. Stop hunting for "For Sale" signs on the side of the road. In 2026, the most lucrative deals aren't listed on public databases where every institutional shark can see them. They're hidden in the shadows of off-market data. Mastering creative financing for multifamily properties requires a systematic approach to hunting. You're looking for specific signals that scream "motivated seller" before the rest of the market even wakes up.
Speed is your greatest asset. We use a 90-day roadmap to move from initial research to a signed contract. This isn't about luck; it's about filtering. You need to identify owners who have high equity, have held the property for over ten years, or live out of state. These signals often indicate a seller who is tired of management headaches or is looking for an exit strategy that doesn't involve a massive tax hit. The faster you find them, the faster you can solve their problem.
To execute this at scale, you must leverage technology. Use Real Estate Radar to filter through off-market leads and pinpoint these exact opportunities. Once you have the list, your outreach must be direct and focused on the seller's needs, not just your desire to buy. Every deal must be analyzed to ensure the creative terms you negotiate don't accidentally kill your cash flow. If the math doesn't work, the deal doesn't work.
Filtering for Success
Target "Mom and Pop" owners. These individual investors are 10x more likely to engage in seller financing than a large corporation. They don't have a board of directors to answer to. They just want a fair price and a reliable exit. Distinguish between a distressed property and a distressed owner. You want the owner who is "done" with the day-to-day grind but owns a property with solid bones. These are the prime candidates for a Master Lease solution where you take over the management burden immediately while locking in a future purchase price.
The Pitch: Scripting Your Win
Your pitch is everything. Start with the "Golden Question" to uncover their true motivation: "If I could give you the price you want, would you be willing to be flexible on the terms?" This shifts the conversation from a battle over price to a collaborative session on structure. Explain the tax benefits of a seller carry-back. Many non-professional owners don't realize they can defer capital gains by receiving payments over time rather than in one lump sum. When they object with "I want all my cash now," show them the math on how much they'll lose to the IRS versus how much they'll gain in interest by acting as the bank. You aren't just buying their building; you're providing them a higher-yield, secured retirement vehicle.
Ready to stop guessing and start closing? Join our Mentorship Program and get the exact scripts we use to turn "no" into a creative "yes."
The Mentorship Advantage: Secure Your Deal with Multifamily Schooled
You've seen the strategies. You know the math. But here's the cold reality: 90% of "creative" deals fall apart at the closing table. Why? Because most investors lack the execution framework to handle the complex legal and financial hurdles of 2026. They struggle with paperwork, lose seller trust, or fail to stack the capital correctly. You don't have to be one of them. Securing creative financing for multifamily properties requires more than just knowledge; it requires a proven system and a mentor who has already cleared the path. Stop guessing. Start winning.
Our Mentorship Program is designed to force your success. We don't just teach you the theory. We provide the "Inner Circle" access to private lenders and creative deal-makers who actually close these transactions. The cost of waiting in 2026 is too high. With multifamily starts projected to fall 5% by the end of the year, the window to acquire assets before the next supply crunch is closing. We provide a 90-day deal guarantee because our system is built on data, not hope. This is your chance to join a fast-moving movement of economic empowerment.
Your Fast-Track to Mastery
Success starts with a foundation. Join the 5-Day Multifamily Challenge to build your base. You'll learn Justin Brennan's proprietary system for navigating the complex financing landscape of 2026. This isn't a passive course. It's an action-oriented sprint designed to move you from curiosity to a signed letter of intent. We remove the fear of failure with our "Deal or We Find You One" promise. If you follow the prescribed methodology, the results are inevitable. You're getting a multi-generational heritage of expertise packaged into a high-impact execution engine.
Next Steps for the Action-Oriented Investor
Take action today. Download the Multifamily Tool Kit to start your analysis immediately. Don't wait for interest rates to drop or for the "perfect" market. Audit your local market for creative opportunities right now using Real Estate Radar to filter the noise. Commit to the 90-day timeline. Your first apartment building is closer than you think. The difference between a dreamer and a mogul is the willingness to seize the current opportunity. The tools are ready. The system is proven. The only missing piece is your commitment to start your journey now.
Claim Your Stake in the 2026 Multifamily Market
The era of relying on traditional bank approvals is over. You now possess the blueprint to navigate high interest rates and restrictive lending. By mastering creative financing for multifamily properties, you can control high-value assets and scale your portfolio at a pace others think is impossible. You've learned how to turn sellers into partners, stack private capital, and use data to find hidden opportunities. Stop watching from the sidelines while others build generational wealth. We provide A-Z training from multi-generational experts and proprietary Real Estate Radar AI software. Our system isn't just about education. It's about execution.
We're so confident in our methodology that we offer a 90-Day Deal Guarantee. Success is no longer a matter of luck. It's a matter of following a proven system. The tools are in your hands. The market is ready. Your future is waiting for you to take the first step toward true independence. Don't let hesitation hold you back from the prosperous future you deserve.
Find Your First Deal in 90 Days; Join the Mentorship Program Now!
Frequently Asked Questions
Is creative financing legal for commercial multifamily properties?
Yes, creative financing is fully legal and widely used in commercial real estate. In 2026, you must comply with the new FinCEN reporting rule, which requires a "Real Estate Report" for non-traditional transfers to legal entities or trusts. As long as you maintain transparency and follow federal disclosure requirements, these strategies are powerful, legitimate tools for building your empire.
How much down payment do I really need for seller financing?
You can often negotiate down payments between 0% and 10%, which is a massive shift from the 25% required by traditional lenders. The exact amount depends entirely on the seller's motivation and the equity they hold in the building. By solving a seller's specific problem, such as management fatigue or tax liability, you can secure high-value assets with significantly less personal capital.
Can I use creative financing if I have a low credit score?
Yes, you can absolutely use creative financing for multifamily properties with a low credit score because the seller acts as the bank. Private sellers are generally more focused on the property's Net Operating Income and your ability to manage the asset than your personal FICO score. This allows you to bypass the rigid hurdles of institutional lending and start scaling your portfolio immediately.
What is the "Subject-To" strategy and is it risky?
The "Subject-To" strategy involves taking over a seller's existing mortgage payments while the original loan stays in their name. The main risk is the "due-on-sale" clause, which gives banks the right to call the loan due if they notice a title transfer. Many professional investors mitigate this risk by ensuring all payments are made on time and maintaining clear communication with all parties involved.
How do I find sellers who are willing to finance the deal themselves?
You find these sellers by targeting off-market data and looking for "Mom and Pop" owners with high equity. These individuals often own their buildings outright and are looking for a steady exit strategy without the stress of daily management. Use specialized software to filter for out-of-state owners or long-term holders who are 10x more likely to accept creative terms than institutional corporations.
What are the tax benefits of seller financing for the person selling the building?
Sellers can defer capital gains taxes by using an "installment sale" structure, receiving their money over several years instead of all at once. This often keeps them in a lower tax bracket and provides them with a consistent, interest-bearing income stream. It turns their equity into a secured retirement vehicle, allowing them to earn interest on the money they would have otherwise paid to the IRS.
Do I need a lawyer to structure a Master Lease Option?
You should always use a qualified real estate attorney to review and finalize your Master Lease Option agreements. These contracts involve management rights, maintenance responsibilities, and future purchase options that must be legally airtight to protect your investment. Paying for professional legal counsel upfront is a small price to pay to ensure your path to ownership is secure and undisputed.
How does creative financing work with existing bank loans?
Creative strategies often involve "wrapping" a new note around the existing bank debt to preserve low interest rates. This is known as a wraparound mortgage, where you pay the seller, and they continue to pay their original lender. This allows you to utilize creative financing for multifamily properties even when the building isn't owned free and clear, maximizing your leverage in any market environment.



