
How to Get a Commercial Real Estate Loan: The 2026 Investor’s Blueprint
What if the bank cared more about your apartment building's cash flow than your personal credit score? Most investors freeze when they see 2026 interest rates hitting 8.75% or hear about the $544 billion in maturing debt. They let fear of rejection or confusion over a 1.20x DSCR stop their dreams. You don't have to be one of them. Mastering how to get a commercial real estate loan is about following a proven system, not begging for a favor. Success in this market is about the deal's performance and your ability to speak the lender's language with total confidence.
You want a clear, step-by-step path to funding that unlocks large-scale apartment investing. We agree that the old way of hoping for the best at the bank is dead. This 2026 blueprint gives you the mastery to present deals that lenders can't ignore even with a 6.75% prime rate. We will break down the exact metrics you need to hit, show you why private debt funds are the new power players, and give you the tools to achieve financial freedom through leverage. It's time to stop the analysis paralysis. Follow this guide to secure your financing and build wealth now.
Key Takeaways
- Stop obsessing over personal credit and learn why the property's income is the ultimate key to unlocking massive wealth.
- Master the "Big Two" metrics, DSCR and LTV, to ensure your deal gets a "green light" from lenders every single time.
- Follow our proven 5-step blueprint on how to get a commercial real estate loan and build a deal package that commands respect.
- Discover how to use cutting-edge AI tools to source off-market gems and beat the competition to the best apartment deals.
- Leverage our systematic approach to bypass the 95% failure rate of solo investors and own your first apartment in 90 days.
Stop Thinking Small: How Commercial Loans Build Massive Wealth
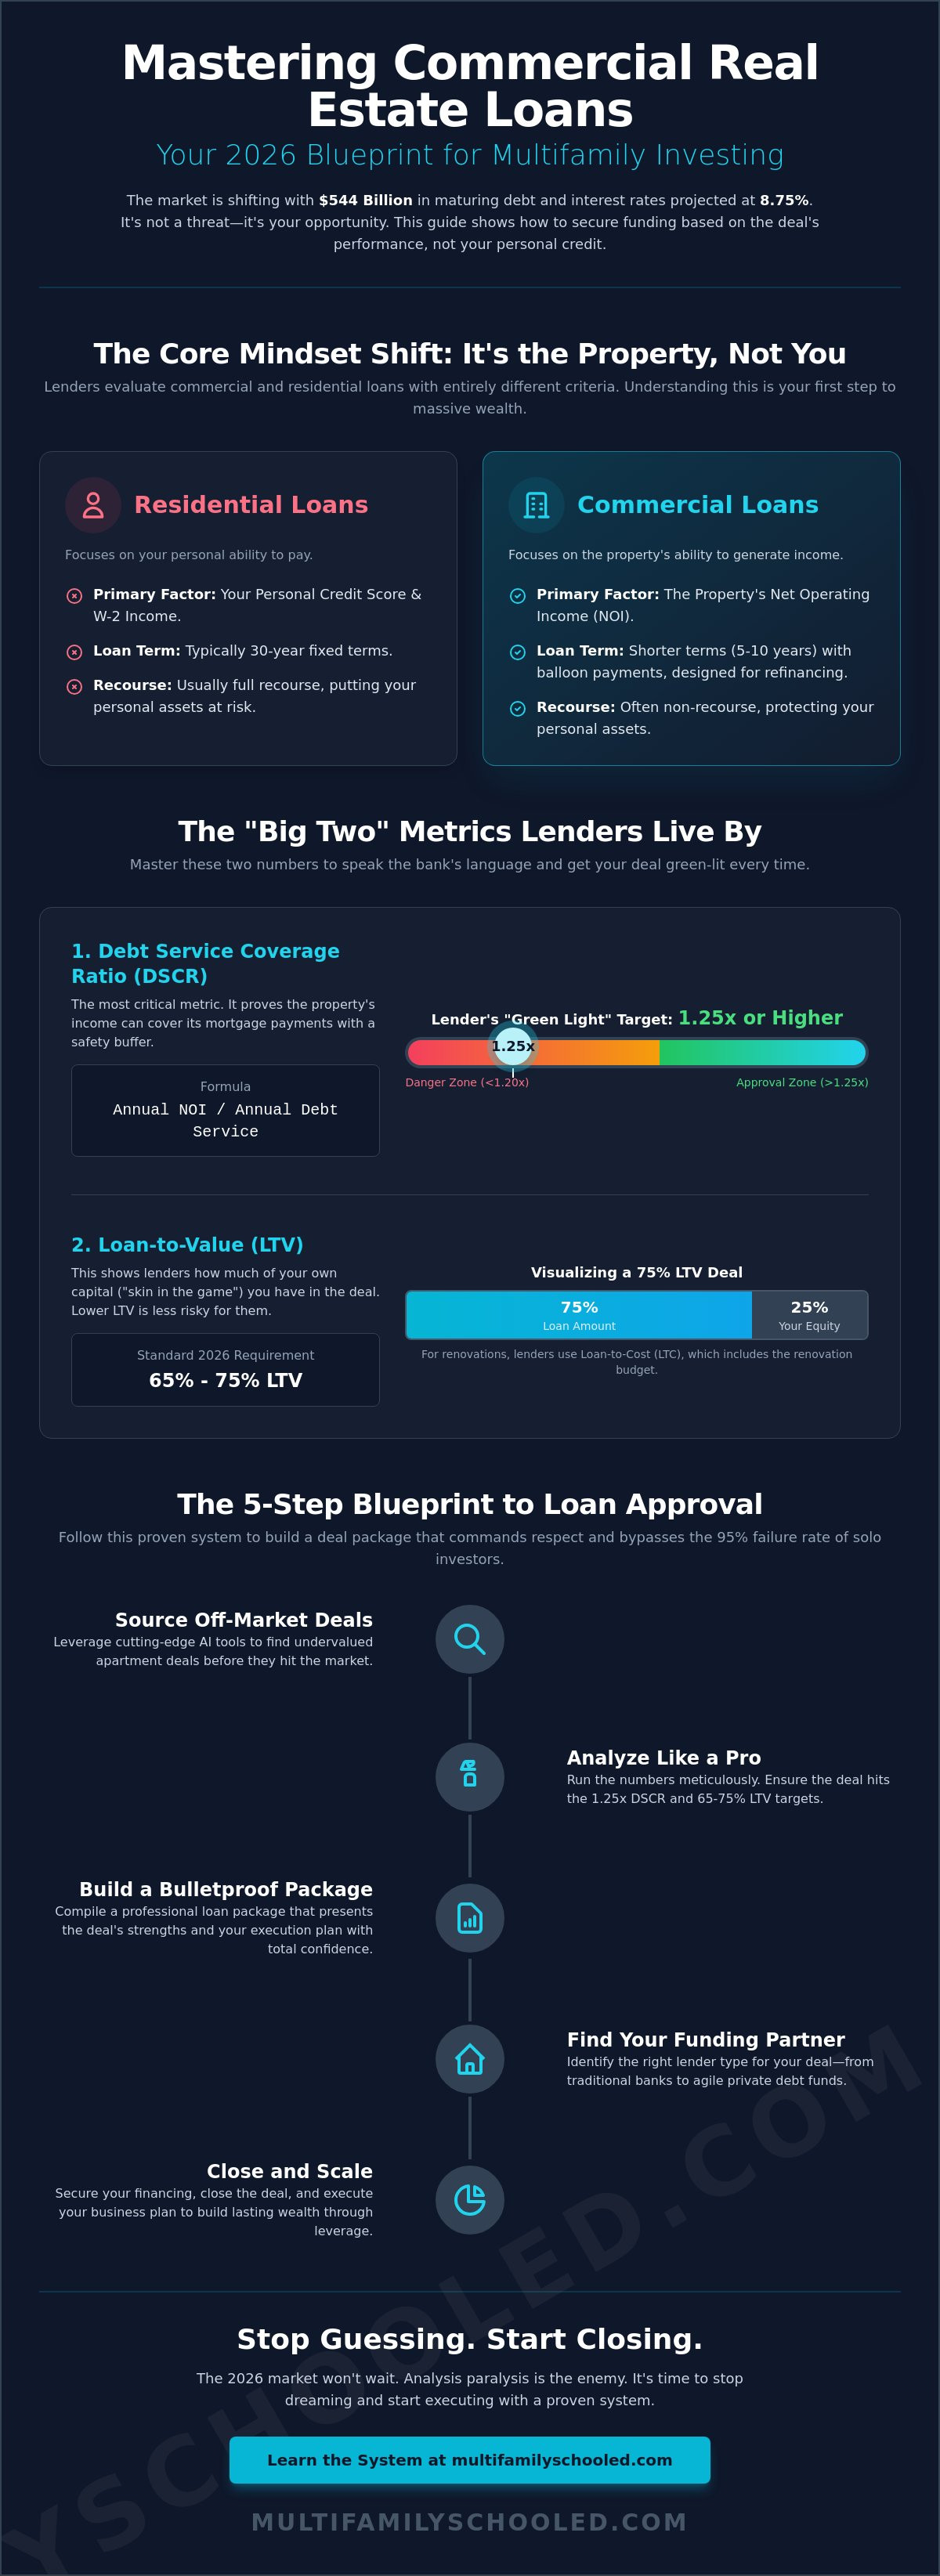
Stop playing small with single-family houses. Residential loans are for where you live; commercial loans are for how you build an empire. In 2026, the biggest mistake you can make is thinking your personal salary is the bottleneck. It's not. A Commercial mortgage is an asset-backed powerhouse. The property's income is the king that dictates your funding. If the building's cash flow is strong, the bank wants to partner with you. This shift in perspective is the first step toward financial freedom.
To better understand the mechanics behind this wealth-building tool, watch this helpful video:
Leverage is your superpower. It allows you to control a $10 million apartment complex with just a fraction of the capital. While others save for decades, you can use a proven system to scale in 90 days. Lenders in 2026 favor multifamily because people always need a roof over their heads. It's the most stable asset class in a shifting economy. Understanding how to get a commercial real estate loan means understanding that you're buying a business, not just a property.
Commercial vs. Residential: The Key Differences
Residential lenders look at your tax returns and W-2s. Commercial lenders look at the Net Operating Income (NOI). If the building makes money, you get the loan. You'll encounter 5 to 10 year balloon payments instead of 30-year fixed terms. This isn't a drawback; it's a strategy to refinance and pull out tax-free equity. You can often secure non-recourse debt. This means the lender can't come after your personal house or car if the deal goes south. It's the ultimate way to protect your legacy while you build it.
The 'Proven System' Mindset
Lenders don't just bet on bricks and mortar. They bet on the pilot. If you're a first-time investor, your biggest hurdle isn't the money; it's the "experience gap." This is where the Mentorship Program changes the game. By leveraging a mentor's track record, you prove to the bank that you have a system for success. You aren't guessing. You're executing. The 2026 market is moving fast. With $544 billion in loans maturing this year, banks are desperate for high-quality operators. Don't wait. Master how to get a commercial real estate loan today and take your seat at the table.
The Numbers That Win: Mastering DSCR and LTV
Lenders don't care about your feelings. They care about the math. If you want to know how to get a commercial real estate loan, you must speak the language of Debt Service Coverage Ratio (DSCR). This isn't just a technicality. It's the pulse of your deal. Forbes confirms that Commercial Real Estate Loans rely heavily on property performance rather than personal credit alone. In 2026, banks aren't taking risks. They want a "margin of safety" because of the $544 billion in maturing debt set to hit the market this year. They need to know the building can pay for itself and then some.
Calculating DSCR Like a Pro
The formula is simple: divide your Annual Net Operating Income (NOI) by your Annual Debt Service. If your building nets $125,000 and the mortgage costs $100,000, your DSCR is 1.25x. This is the industry standard "Green Light." Anything lower, and you're in the danger zone for most multifamily deals. You can boost this number before you even apply. Cut unnecessary expenses. Audit your utility bills. Small tweaks to your NOI can lead to massive jumps in the funding you qualify for. Lenders love efficiency.
LTV and LTC: Know Your Ratios
Loan-to-Value (LTV) is your skin in the game. In 2026, lenders have pulled back from the aggressive lending of previous years. Expect to see requirements between 65% and 75% LTV for standard acquisitions. If you're planning a heavy lift, look at Loan-to-Cost (LTC). This covers the acquisition plus the renovation budget. Don't let a high down payment stop you. Many successful students use gap funding or bring in partners to bridge the equity gap. It's about controlling the asset, not owning 100% of the debt.
Net Operating Income is the engine that drives your loan approval. It's your gross income minus operating expenses. In 2026, lenders are scrutinizing expenses more than ever due to rising insurance costs. If you can show a bulletproof NOI, you win. If you feel overwhelmed by these metrics, you can use our Multifamily Tool Kit to analyze your deals in seconds. Mastery of these numbers is what separates the dreamers from the owners. Take the math seriously. Secure your funding. Build your empire.
Bank, SBA, or Agency? Finding Your Perfect Funding Match
Choosing the wrong lender can kill your deal before it starts. You have mastered the math of DSCR and LTV. Now you must find the perfect funding match for your specific asset. In 2026, the landscape is shifting. Traditional banks are pulling back, but new doors are opening for those who know where to look. Whether you are chasing a 20-unit apartment complex or a small retail strip, your choice of lender determines your speed to wealth. Success in this market requires you to know exactly how to get a commercial real estate loan that fits your long-term goals.
Conventional bank loans remain a staple for local investors. They are best for smaller deals where a face-to-face relationship matters. As of May 2026, expect rates between 5.21% and 8.75% depending on your property type and location. Banks often offer more flexibility on loan structures but usually require a personal guarantee. If you want to scale faster without risking your personal assets, you need to look at the "big leagues" of multifamily financing. This is where you move from owning a property to building a legacy.
Agency Lending: The Multifamily Secret
Fannie Mae and Freddie Mac are the gold standards for a reason. They love apartment buildings with 5 or more units. Why? Because multifamily is proven to be the most stable asset class in any economy. In early 2026, Fannie Mae Small Loans are hovering between 5.81% and 7.91%. The biggest win here is the non-recourse benefit. If the deal fails, the bank takes the building, not your personal bank account. This allows you to sleep better at night while controlling millions in real estate. Most agency lenders require at least 90% occupancy for 90 days, so make sure your operations are tight before applying.
The SBA Advantage for Business Owners
If you plan to run your business out of your property, SBA commercial real estate loans are a powerful weapon. Programs like the SBA 504 allow you to get in with as little as 10% down. This preserved capital can be used to grow your business instead of being locked in a building. Watch out for the "51% occupancy" rule. To qualify for these high-leverage terms, your business must occupy more than half of the square footage. If you are strictly looking for passive income from tenants, pivot back to conventional or agency financing.
Sometimes speed is more important than the interest rate. Hard money and bridge loans offer fast capital for "value-add" opportunities that traditional banks won't touch. These are short-term solutions to fix a property and increase the NOI. Once the building is stabilized, you can refinance into a long-term loan. Understanding how to get a commercial real estate loan means knowing which tool to pull from your belt for every specific deal. If you need help picking the right path, our Mentorship Program provides the hands-on guidance to navigate these choices with total certainty.
The 5-Step Blueprint to Securing Your Commercial Loan
Stop guessing. Start executing. Securing a loan in 2026 isn't about luck; it's about following a systematic blueprint. If you want to know how to get a commercial real estate loan, you need to act like a pro before you ever dial a lender's number. This 5-step process is designed to turn you into a high-level operator that banks trust. It's time to trade your hesitation for a proven method that gets results.
Step 1: The Ultimate Deal Package
Your deal package is your first impression. If it looks amateur, you're dead on arrival. A professional package includes an executive summary, current rent rolls, and the last 12 months of financials, often called a T-12. This shows the lender you understand the property's pulse and its potential. Use the Multifamily Tool Kit to organize this data into a format that lenders recognize. A clean, professional presentation accounts for 50% of the battle in getting that first "yes" from a big bank.
Knowing how to get a commercial real estate loan is useless if you don't have a deal that pencils out. Use Real Estate Radar AI to find off-market gems where the competition is thin. Once you find a target, run your "Pre-Flight Check." Run the numbers through a Green Light analyzer to ensure the DSCR and LTV meet the 2026 standards of 1.25x and 75% respectively. If the property doesn't hit these marks, walk away immediately. Don't fall in love with a bad deal.
Step 4: Mastering the Lender Interview
When you get the meeting, you must flip the script. Don't just answer questions; ask them. Ask about their current appetite for multifamily or their typical appraisal timelines. This shows you're a serious player who values their time. If they hit you with the "lack of experience" objection, don't flinch. Pivot to your mentorship fallback. Explain that you are working with a 3rd generation investor who has "hands on street smarts." This instantly bridges the gap and builds the trust necessary to move toward closing.
Finally, move into the due diligence phase. This 90-day sprint involves third-party appraisals and environmental reports. In 2026, lenders are especially focused on rising insurance costs and operating expenses, so get your quotes early. Closing the deal is about persistence and precision. You have the blueprint, but you don't have to walk the path alone. Join our Mentorship Program today and let us help you close your first apartment deal with total confidence.
Stop Guessing and Start Closing: The Multifamily Schooled Way
You've seen the blueprint. You know the numbers. You understand the lenders. But here is the cold, hard truth: 95% of solo investors fail in their first year. They get stuck in analysis paralysis or crushed by a single mistake in their deal package. Don't go it alone. In the fast-moving 2026 market, you need more than just information. You need a proven system and the "Hands-On Street Smarts" of a 3rd generation investor like Justin Brennan. Real success isn't about working harder; it's about following a path that's already been paved for you.
Most guides on how to get a commercial real estate loan ignore the role of technology. They leave you to struggle with manual spreadsheets and outdated data. We close that gap. Our system integrates proprietary software to help you analyze deals in seconds, not hours. This technological edge is why our students are closing deals while others are still staring at rent rolls. We turn the complex process of securing financing into a predictable, repeatable machine. It's time to stop playing small and start using the tools that the pros use to build massive wealth.
The Mentorship Advantage
Wealth is a team sport. When you join our community, you aren't just buying a course; you're joining a circle of VIP investors who are actually closing deals in today's economy. You'll master the "Fast 5 Method" for rapid portfolio scaling. This method isn't theory. It's a battle-tested strategy for moving from zero to owning hundreds of units in record time. Lenders treat you differently when they know you have an elite team behind you. It changes the entire conversation. Apply for the Mentorship Program today to see if you qualify for this exclusive group.
Your 90-Day Action Plan
We don't do vague promises. We do results. That's why we offer the 90-Day Guarantee: We help you find a deal in 90 days or we give one to you. Imagine owning your first apartment building before the end of this quarter. It's possible when you stop guessing and start following the blueprint. This is your moment to unlock financial freedom and build a legacy for your family. The 2026 market won't wait for you to feel "ready." Take the first step toward your new life right now. Join our next Live Workshop or download our eBook to jumpstart your journey. Your future self is waiting. Take the challenge and secure your first commercial loan today.
Your Path to Financial Freedom Starts Now
The blueprint is in your hands. You now understand that property income, not just personal credit, is the key to building an empire. You know how to master DSCR ratios and which lenders to target in the 2026 market. Mastering how to get a commercial real estate loan is the single most powerful skill you can develop to achieve true wealth. Don't let this knowledge sit on a shelf. The gap between where you are and where you want to be is action.
Leverage the 3rd Generation Multifamily Expertise that's been featured on major financial networks. Our guaranteed deal finding system removes the guesswork and puts you in the driver's seat. You don't have to navigate this alone. Take the first step toward a life of passive income and security. Your future is waiting for you to claim it. Ready to Own Apartments in 90 Days? Join the Mentorship Today! Success is a choice you make right now. We'll see you at the closing table.
Frequently Asked Questions
Is it harder to get a commercial loan than a residential one?
It is often easier to qualify for a commercial loan because the lender prioritizes the property's income over your personal paycheck. While residential loans focus on your W-2 salary and debt-to-income ratio, commercial financing looks at the Net Operating Income. If the asset generates enough cash to cover the mortgage, the bank wants to partner with you. This allows you to build massive wealth regardless of your personal income.
How much down payment is required for a commercial real estate loan in 2026?
You should expect to provide a down payment of 25% to 35% for conventional commercial mortgages in 2026. However, you can secure funding with as little as 10% down using SBA 504 or 7(a) programs. Lenders currently prefer a Loan-to-Value ratio between 65% and 75% for most acquisitions. This ensures the property has enough equity to handle market shifts while you focus on maximizing your cash flow and building passive income.
What is the minimum credit score for a commercial loan?
Most lenders look for a minimum credit score between 660 and 680 to approve a commercial loan. While your score is a factor, it is not the deal-breaker it is in residential lending. Lenders care more about the cash flow of the asset and your experience. If your score is lower, you can often bridge the gap by partnering with a mentor who has a stronger financial profile and proven track record.
Can I get a commercial loan with no experience?
You can absolutely get a commercial loan with no experience by leveraging a mentor's track record or a proven management system. Lenders bet on the operator's ability to execute the business plan. If you are new, joining a mentorship program provides the hands-on street smarts that banks demand. This strategy turns you from a risky beginner into a strategic partner. It is the fastest way to unlock the door to large-scale apartment investing.
What is a DSCR and why does it matter so much?
The Debt Service Coverage Ratio (DSCR) measures the property's ability to cover its annual debt payments using its Net Operating Income. It matters because it is the primary metric for how to get a commercial real estate loan that lenders use to judge risk. In 2026, most multifamily lenders require a minimum DSCR between 1.20x and 1.30x. If your building doesn't hit these marks, you won't get funded. Mastery of this number is key.
How long does the commercial loan process typically take?
The commercial loan process typically takes between 45 and 90 days to move from application to closing. This timeline includes third-party appraisals, environmental reports, and thorough legal reviews by the lender. You can speed up this process by having a professional deal package ready before your first meeting. Being organized shows the bank you are a serious operator and can often shave weeks off the standard due diligence period for your deal.
What are the current interest rates for commercial loans?
Current interest rates for conventional commercial mortgages range from 5.21% to 8.75% as of May 2026. Fannie Mae Small Loans currently sit between 5.81% and 7.91%. These figures are tied to the Wall Street Journal Prime Rate of 6.75% and a 10-Year Treasury yield of 4.26%. Understanding these numbers is vital when learning how to get a commercial real estate loan that scales your wealth and builds long-term financial freedom.
Can I use a commercial loan to buy an apartment building?
You can and should use a commercial loan to buy any apartment building with 5 or more units. These properties are classified as commercial real estate, which allows you to tap into non-recourse debt and higher leverage. This is the primary method used to build empires and achieve financial freedom. Commercial loans focus on the building's performance, allowing you to control millions in assets that a residential mortgage would never cover.



