
How to Build Business Credit for Real Estate Investing in 2026
Relying on personal credit is the single fastest way to choke your real estate growth. You already know the sheer frustration of watching a maxed-out debt-to-income ratio stall your next acquisition, or the constant fear of risking your family's personal assets on a single deal. When you hit that ceiling, learning how to build business credit for real estate investing becomes your ultimate growth vehicle. Business credit is the strategic engine that decouples your portfolio expansion from your personal balance sheet.
You can break free from personal underwriting limits once and for all. You will master the exact step-by-step blueprint to build a clean corporate profile, protect your personal net worth, and position your business for scalable institutional funding. Here is your operational roadmap to establishing vendor tradelines, moving through commercial credit tiers, and securing the financing you need to close apartment and commercial assets with total confidence.
Key Takeaways
- Decouple your growth from personal debt-to-income limits and insulate your personal assets from property-level liability.
- Establish an authentic, lender-compliant entity foundation to pass automated underwriting checks without friction.
- Execute the 4-tier tradeline progression to accelerate corporate credit depth and unlock commercial financing.
- Discover the proven system of how to build business credit for real estate investing to fund earnest money, renovations, and multifamily deals.
- Monitor your reporting profiles across all three major commercial bureaus to maintain clean, scalable borrowing power.
Why Real Estate Investors Must Separate Business Credit from Personal Credit
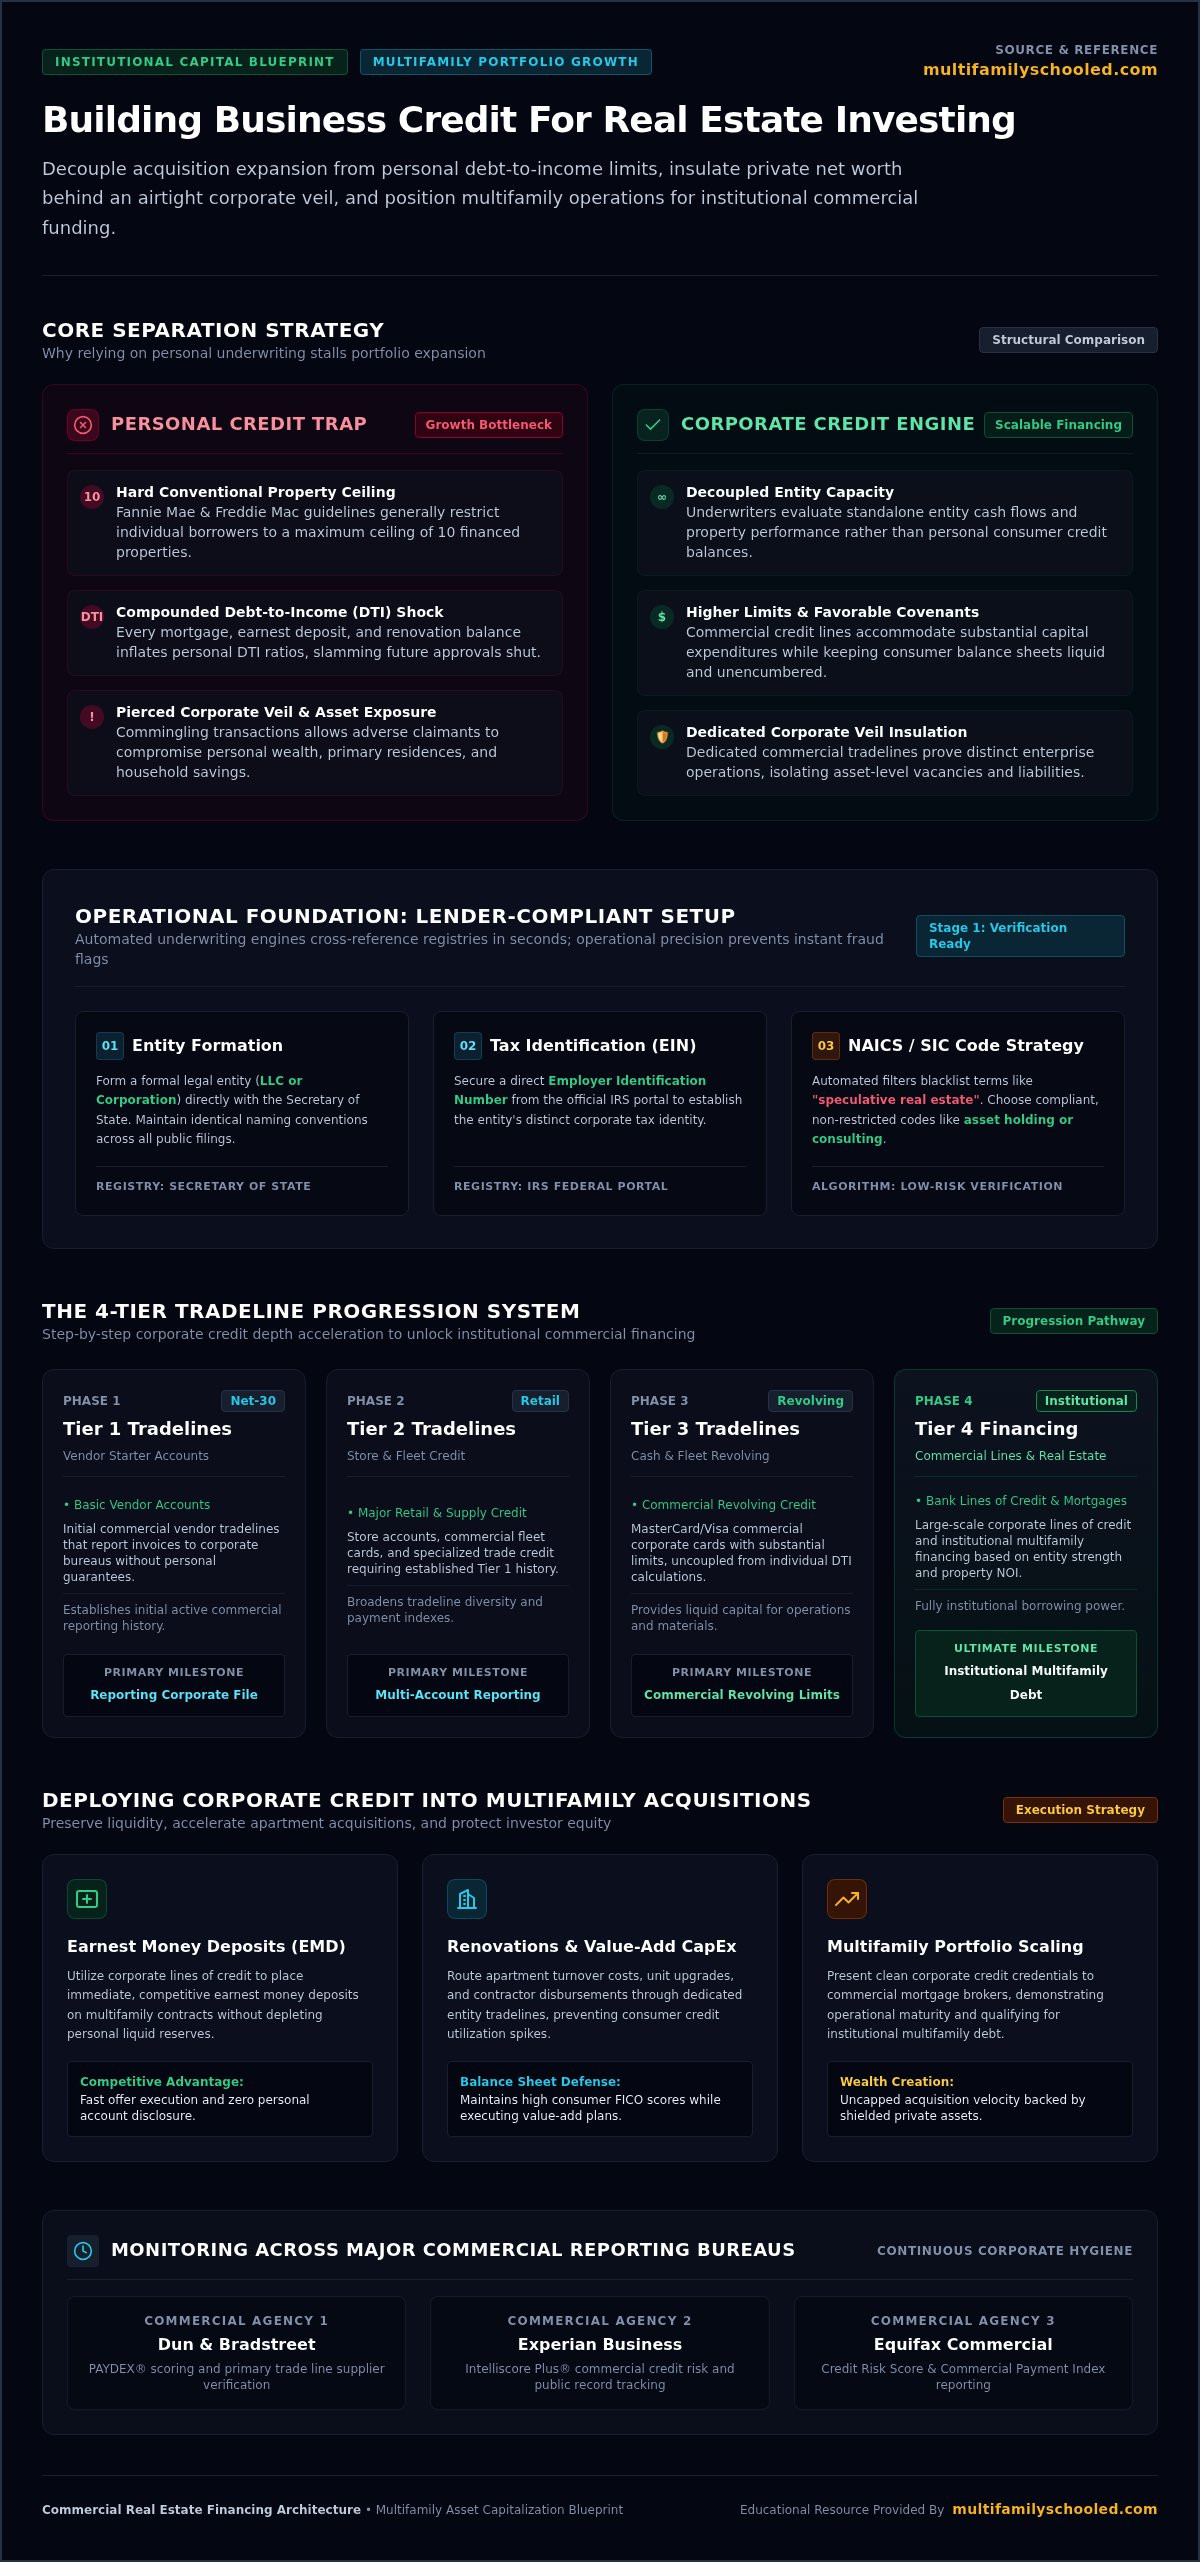
Personal borrowing limits will strangle your portfolio before you hit your true stride. When you rely solely on your consumer credit profile, every mortgage, renovation loan, and earnest money deposit inflates your personal debt-to-income (DTI) ratio. Lenders slam the door shut. Mastering how to build business credit for real estate investing removes this bottleneck, establishing an independent entity profile capable of carrying commercial obligations without choking your personal finances.
To master the foundational mechanics of corporate capitalization, watch this breakdown of real estate credit fundamentals:
Separation changes everything. Institutional lenders and commercial mortgage brokers want to see operational maturity. By routing your property capital expenditures through an entity line of credit, you gain access to substantially higher borrowing limits with favorable covenants, while keeping your personal balance sheet liquid and unencumbered.
The Hidden Trap of Personal Guarantees and DTI Limits
Conventional financing models punish aggressive growth. Residential Fannie Mae and Freddie Mac guidelines generally restrict individual investors to a hard ceiling of ten financed properties. Put massive renovation costs on personal revolving credit, and your consumer utilization rates skyrocket, tanking your credit scores just when you need liquidity. Commercial underwriters look at debt differently. They evaluate your entity's cash flows and standalone track record rather than counting your personal credit balances against you.
Corporate Veil Protection and Risk Mitigation
Commingling your personal and business transactions destroys your legal shield. If a tenant files a lawsuit or a contractor files a lien, mixed bank records allow opposing attorneys to pierce the corporate veil, placing your primary residence and private savings at risk.
- Isolate liability: Dedicated commercial tradelines prove your entity operates as a distinct commercial enterprise.
- Shield your family: Unexpected market adjustments or asset-level vacancies will not damage your personal credit rating.
- Accelerate deals: Understanding how to build business credit for real estate investing positions your LLC to secure commercial assets with institutional credibility.
Executing this structure allows you to scale larger multifamily acquisitions safely, knowing your private wealth remains locked behind an airtight legal wall.
Lender-Compliant Entity Setup: Laying the Legal and Operational Foundation
Automated underwriting algorithms will reject your loan application in seconds if your records do not match. Institutional lenders do not manually review every detail when you first apply; they deploy automated verification engines to cross-reference public records, corporate filings, and commercial registries. A single typo or misclassified industry code triggers an immediate fraud flag. If you want to know how to build business credit for real estate investing that actually holds up under scrutiny, you must establish an authentic, fully compliant commercial footprint from day one.
Reviewing actionable steps for building business credit shows that commercial credibility starts with operational precision. If you need standard legal layouts and document trackers to stay organized during setup, leverage the structured frameworks inside our multifamily tool kit.
Entity Selection, EIN, and NAICS Code Strategy
Form your legal entity (LLC or Corporation) directly through your Secretary of State. Once confirmed, request a free Employer Identification Number (EIN) straight from the IRS portal. Your North American Industry Classification System (NAICS) and Standard Industrial Classification (SIC) codes require strategic care. Many automated underwriting systems instantly blacklist high-risk labels like "speculative real estate" or "credit intermediation." Select compliant, non-restricted operational codes such as real estate asset holding, consulting, or general investment management to keep automated pathways open.
Establishing Operational Credibility for Underwriters
Lenders demand proof that you run a legitimate physical enterprise, not a fly-by-night operation from a kitchen table. Meeting commercial standards requires executing three physical milestones:
- Commercial physical location: Register a verified physical office or dedicated executive suite. Never use a residential address or basic P.O. Box.
- Directory listing: Establish a dedicated local business phone line and register it with the national 411 directory database.
- Digital footprint: Launch an active company website with matching branded domain email addresses. Skip free consumer inboxes.
Opening Dedicated Commercial Banking Accounts
Take your stamped formation documents, operating agreement, and EIN confirmation directly to a commercial bank. Fund your dedicated business checking account immediately with initial operational equity. Commercial lenders track your average daily balance to calculate internal bank rating scores, which heavily influence future line-of-credit limits. Keep personal capital completely separate. Move capital exclusively through structured equity contributions or formal operating distributions accompanied by internal bookkeeping resolutions.
Locking down these institutional checkpoints ensures you master how to build business credit for real estate investing with an airtight entity that clears automated audits smoothly.
The 4-Tier Tradeline System: Step-by-Step Credit Acceleration
Walking straight into a bank to ask for an uncollateralized line of credit without an established corporate history guarantees a swift denial. Business credit is not granted on potential; it is earned through progressive tiers of verified reporting. Moving through a structured framework is the core of how to build business credit for real estate investing. Each tier establishes the verifiable payment track record required to unlock higher limits and institutional trust.
Tier 1: Establishing Net 30 Vendor Tradelines
Your foundation begins with Tier 1 vendor accounts. These are business suppliers offering net 30 payment terms that report directly to Dun & Bradstreet, Experian Business, and Equifax Small Business. Set up accounts with commercial office, shipping, and maintenance vendors. Buy standard operational supplies, then pay your invoices well before the 30-day window closes. Securing five distinct reporting tradelines generates your baseline Dun & Bradstreet PAYDEX score, giving underwriters concrete evidence of transactional reliability.
Tier 2: Unlocking Fleet and Store Credit Accounts
Once Tier 1 tradelines reflect on your commercial reports, advance immediately to Tier 2 store and fleet accounts. These credit lines expand your borrowing capacity while adding diverse trade categories to your files.
- Target store accounts: Secure accounts with major building supply retailers, hardware distributors, and national fuel stations.
- Fund operations: Channel everyday property maintenance, unit turnover hardware, and travel expenses directly through these cards.
- Manage limits: Keep your credit utilization below 25 percent across all reporting accounts to maximize bureau score progression.
Tier 3 & 4: Graduating to Unsecured Revolving Cash Lines
Tier 3 consists of major revolving commercial cards tied directly to your entity EIN. Emerging fintech solutions like Brex and Ramp report to major commercial bureaus, while conventional issuers like Chase or American Express provide broad spending power. While brand-new business entities typically require a personal guarantee initially, these cards create substantial commercial reporting data that stays isolated from your personal credit bureaus as long as payments remain current.
Finally, you arrive at Tier 4: uncollateralized bank lines of credit and institutional cash facilities. Achieving this level allows your business to draw operating capital for earnest money deposits, architectural studies, and working cash buffers. Mastering this tiered ladder transforms how to build business credit for real estate investing from random guesswork into a systematic operational machine.
Deploying Business Credit to Finance Real Estate and Multifamily Deals
Credit lines are not trophies; they are transactional tools. When you analyze multifamily deals, commercial lenders scrutinize property net operating income and debt service coverage ratios. But they also evaluate your entity's borrowing track record. Mastering how to build business credit for real estate investing gives you the liquidity to execute quickly when prime deals surface.
Funding Earnest Money, Due Diligence, and Property Renovations
Liquidity wins deals. When negotiating purchase contracts, speed establishes credibility. Deploy corporate credit facilities to fund earnest money deposits instantly without waiting for wire transfers from personal accounts. Utilize zero-percent introductory commercial lines to cover critical due diligence expenses, including environmental assessments, mechanical inspections, and commercial appraisal fees.
- Execute value-add projects: Fund unit interior renovations, appliance packages, and common area upgrades directly through trade lines.
- Protect operational cash: Keep physical cash in reserve to handle emergency tenant turnover and property repairs.
- Refinance and repay: After completing value-add renovations and stabilizing rental revenue, execute a permanent agency refinance to clear short-term revolving balances.
Transitioning from Recourse Debt to Non-Recourse Commercial Loans
Breaking past smaller residential holdings requires upgrading your financing structure. Properties with five or more units qualify for commercial debt, where underwriters evaluate the asset's financial performance over your personal tax returns. As your entity builds a mature commercial credit history, you qualify for non-recourse debt packages.
Non-recourse commercial loans eliminate personal liability for balance repayment if unexpected economic shifts disrupt property operations. Lenders retain claims only against the asset itself, outside standard carve-outs for intentional fraud or gross negligence. Seasoned corporate credit files provide institutional debt funds and agency lenders with the verifiable operational history needed to secure these institutional financing terms.
Understanding how to build business credit for real estate investing bridges the gap between small-scale rentals and institutional apartment complexes. Ready to scale your portfolio and acquire cash-flowing apartment communities? Join the Multifamily Schooled mentorship program to master commercial underwriting, locate high-yield assets, and deploy debt like a seasoned operator.
Monitoring, Maintaining, and Scaling Your Corporate Credit Profile
Building high-limit tradelines is only half the battle. If you fail to protect your commercial files, clerical errors, outdated public filings, or unresolved vendor disputes can quietly destroy your borrowing capacity. Maintaining vigilance across all reporting agencies ensures your business stays primed for rapid funding. True mastery of how to build business credit for real estate investing means running ongoing audits and building an entity architecture capable of scaling across multiple property acquisitions.
Mastering Commercial Credit Bureaus: D&B, Experian, and Equifax
Unlike personal credit scores that run on a 300 to 850 scale, business scoring models follow different rules. Dun & Bradstreet calculates the PAYDEX score on a 1 to 100 spectrum. A score of 80 simply reflects paying on time; achieving a score above 80 requires paying invoices well before the net terms mature. Experian Intelliscore Plus evaluates overall commercial default risk, factoring in public records and collection filings. Pull your reports quarterly from Dun & Bradstreet, Experian Commercial, and Equifax Small Business. Dispute inaccurate delinquencies immediately with documentation to maintain parity across all three repositories.
Portfolio Scaling and Holding Company Architecture
As you expand from single acquisitions into larger apartment complexes, running every deal through one operating entity creates unnecessary liability. Experienced investors deploy a two-tier holding architecture to streamline credit growth:
- Parent management entity: Establish a master operating LLC that builds primary tradelines, secures commercial credit lines, and handles operational vendor relationships.
- Asset-specific holding LLCs: Form standalone special purpose entities (SPEs) to hold title to individual properties, leasing operational control back to your master entity.
- Preserve state standing: Calendar annual Secretary of State franchise filings and commercial registry renewals to prevent automated administrative dissolutions.
This holding structure lets you cross-utilize corporate credit lines for earnest money and working reserves without commingling distinct physical properties. Protect your legal fortress while continually expanding your borrowing power. If you want to master the complete operational framework to source, evaluate, and acquire scalable apartment deals, take advantage of our free training resources to take decisive action today.
Applying this disciplined oversight system ensures your knowledge of how to build business credit for real estate investing translates directly into long-term commercial wealth.
Take Command of Your Capital and Scale Your Portfolio Today
Stop letting consumer debt caps dictate the size of your real estate empire. Establishing a compliant corporate entity, progressing systematically through the four credit tiers, and safeguarding your commercial files insulates your family's private assets while unlocking institutional purchasing leverage. Mastering how to build business credit for real estate investing transforms commercial debt from a roadblock into your greatest growth catalyst.
Don't navigate commercial underwriting alone. Led by Justin Brennan, our comprehensive ecosystem combines deal finding, rigorous property analysis, and financing strategy into a proven framework used by hundreds of active investors scaling commercial multifamily assets nationwide. You have the operational blueprint. Now take decisive action to control your financial destiny. Accelerate your multifamily portfolio and secure funding through our elite Mentorship Program!
Frequently Asked Questions
Can I build business credit for real estate investing without using my SSN?
Yes, you can establish foundational vendor credit exclusively using your Employer Identification Number (EIN). When mastering how to build business credit for real estate investing, Tier 1 net 30 suppliers and select modern corporate cards issue credit directly to your business identity without checking personal consumer bureaus. However, unlocking high-limit institutional bank revolvers often requires an initial personal guarantee until your corporate entity builds substantial verified commercial depth.
How long does it take to establish a usable business credit profile for acquisitions?
Establishing an active, scored corporate profile generally takes 60 to 90 days of disciplined execution. You need roughly 30 days to obtain your EIN, register your D-U-N-S number, and secure initial vendor accounts. Once those vendors invoice and report your prompt payments across a couple of billing cycles, bureaus generate your core commercial scores, allowing you to advance into Tier 2 and Tier 3 credit lines.
What is a PAYDEX score, and what number do commercial lenders look for?
The PAYDEX score is Dun & Bradstreet's proprietary dollar-weighted numerical rating ranging from 1 to 100. Commercial underwriters look for a score of 80 or higher. Achieving an 80 signifies that your business consistently pays invoices exactly on the due date. To reach an elite score of 90 to 100, you must make a habit of paying invoices 20 to 30 days before terms expire.
Can a brand-new LLC qualify for unsecured business lines of credit?
A newly formed LLC can qualify for business credit lines, but approval terms depend on structural execution. Fintech issuers and major commercial card providers regularly approve fresh corporate entities that show clean public filings, legitimate operational addresses, and steady depository balances. While brand-new business entities typically require a personal guarantee during early phases, those balances report strictly to commercial registries rather than your personal credit.
Does business credit eliminate the need for a personal guarantee on mortgages?
Building strong business credit prepares you for non-recourse debt, but it does not eliminate personal guarantees on day one. Smaller 1-to-4 unit residential properties almost always require a personal recourse guarantee. Conversely, commercial lenders and agency programs financing multifamily properties with five or more units routinely offer non-recourse terms to seasoned corporate entities that demonstrate stable property net operating income and healthy corporate balance sheets.
Which major credit bureaus track business credit scores for real estate companies?
Commercial profiles are tracked by three primary reporting agencies: Dun & Bradstreet, Experian Business, and Equifax Small Business. Dun & Bradstreet tracks promptness via your D-U-N-S profile and PAYDEX score. Experian calculates the Intelliscore Plus model to evaluate risk of commercial default. Equifax monitors payment performance across business credit cards, banking facilities, and commercial leases to generate an overall credit score.
How do I fund down payments using business credit lines legally?
You can deploy business credit for acquisition capital as long as you maintain full transparency with your primary commercial lender. Investors frequently draw on corporate credit lines to fund earnest money deposits, engineering reports, or initial equity injections. Commercial underwriters require full disclosure of all debt sources during property review to verify that total asset-level revenue easily covers every operating expense and debt service obligation.



