
Creative Multifamily Financing: Skip the Banks in 2026
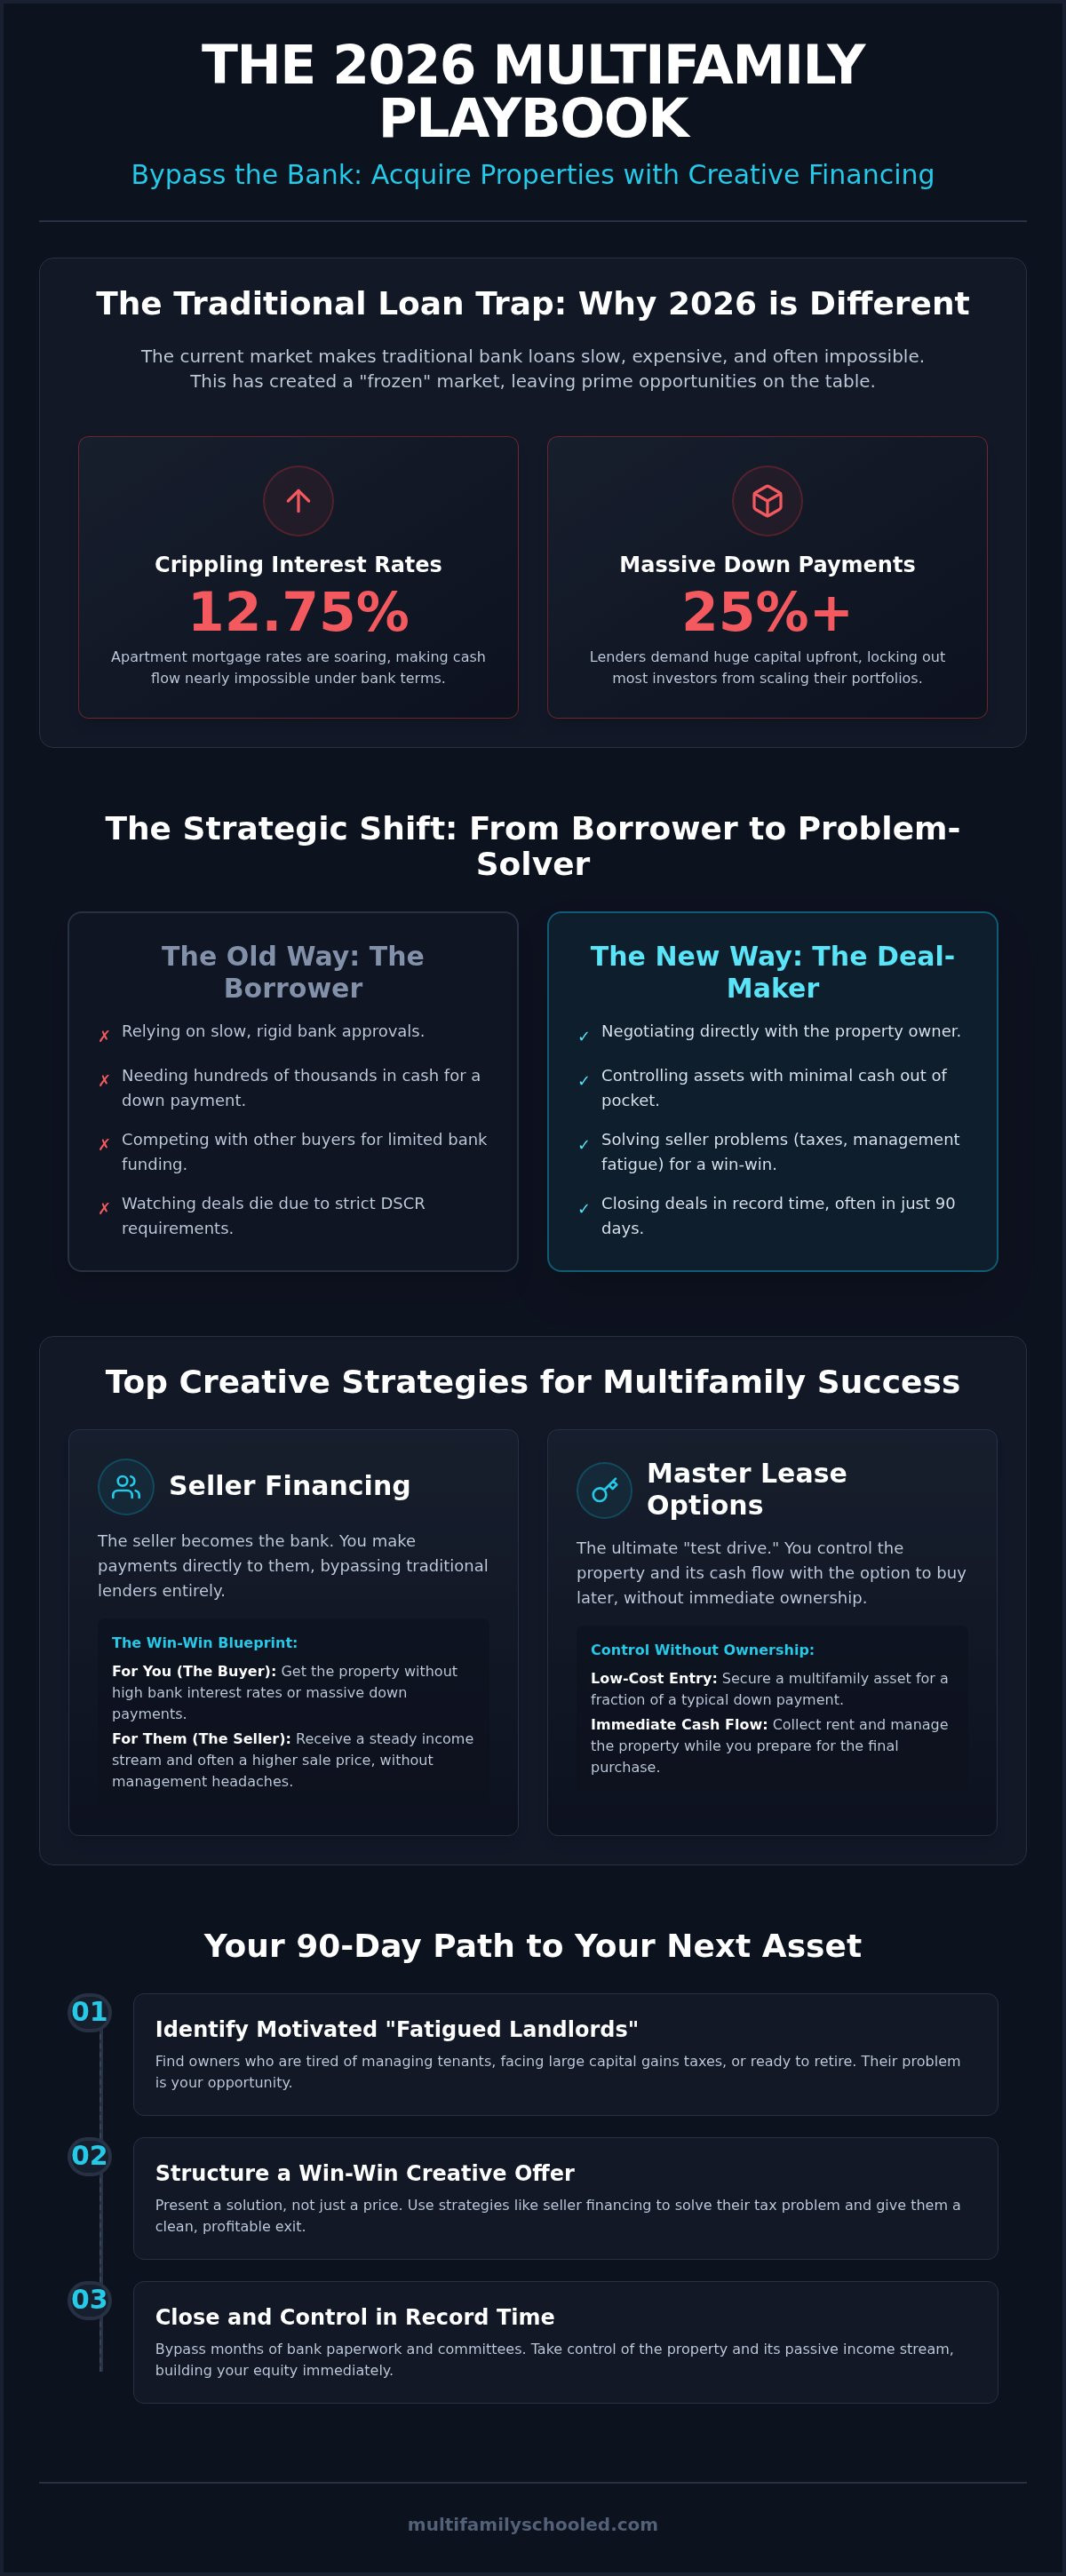
Traditional bank loans are the slowest and most expensive way to build a real estate empire in 2026. You've seen the current market data. With apartment mortgage interest rates climbing as high as 12.75% and lenders demanding massive 25% down payments, the math for most standard deals simply doesn't work. It's exhausting to watch cash-flowing opportunities slip away because a bank's rigid checklist says no. You feel stuck, but the reality is that the most successful investors aren't waiting in line at the bank. They're using creative financing for multifamily properties to bypass these hurdles entirely.
Stop being a borrower and start being a strategic deal-maker. I'm going to show you how to master the exact strategies used by top-tier investors to acquire apartment buildings without traditional lending headaches. You'll learn to solve seller problems while securing assets with minimal cash out of pocket. This guide reveals how to control property and achieve passive income through equity in record time. We'll explore seller financing, the impact of the 21st Century ROAD to Housing Act, and the proven methods to land your next multifamily asset in just 90 days.
Key Takeaways
- Discover why 2026’s "higher for longer" interest rates make traditional bank loans obsolete and how to pivot toward faster, more profitable acquisition methods.
- Master the "Big Three" strategies for creative financing for multifamily properties to control high-value assets without the burden of a 20% down payment.
- Identify motivated "Fatigued Landlords" and use tax-advantageous deal structures to solve their problems while securing your passive income.
- Implement a ruthless 90-day action plan using specialized Deal Finding Software to locate and close off-market apartment deals.
- Shift from a DIY mentality to a proven framework that allows you to bypass bank hurdles and build equity through strategic property control.
Why Creative Financing is the Game-Changer for 2026 Investors
The 2026 lending market is a battlefield. If you're still trying to use 2021 tactics, you're already behind. Banks have tightened their grip. Interest rates for apartment mortgages now swing between 5.41% and 12.75%. These aren't just numbers on a page; they're deal killers for anyone relying on traditional debt. The reality is that banks are scared, and they're passing that fear onto you through impossible requirements. Creative financing isn't just a "backup plan" anymore. It's the only way to stay in the game while others are forced to the sidelines.
To better understand this concept, watch this helpful video:
The Lending Gap in the 2026 Market
Traditional loans are failing because of the Debt Service Coverage Ratio (DSCR). With current rates, most properties don't generate enough income to satisfy a bank’s strict safety margins. This has created a "frozen" market. Sellers are ready to move, but buyers can't get funded. It's a stalemate that leaves massive apartment buildings sitting idle. Creative financing for multifamily properties thaws this frozen market by letting you negotiate directly with the person who actually owns the asset. You don't need a loan committee's permission to build wealth.
Winning Without a Massive Bank Account
The old myth says you need a 20% or 25% down payment to play in the multifamily space. That's a lie designed to keep you small. Saving up hundreds of thousands of dollars takes years, and by the time you have the cash, the best deals are gone. Contrast that with a strategic, creative approach. You can control a property and its cash flow in 90 days by using equity and terms instead of just raw cash. Speed is your ultimate competitive advantage. While your competitors are filling out 50-page bank applications, you're already collecting rent and building equity.
Success in 2026 requires a total mindset shift. You have to stop acting like a "buyer" looking for a handout and start acting like a "problem solver" providing a solution. Sellers are facing massive capital gains hits or are simply tired of managing tenants. When you offer creative terms, you aren't just buying a building. You're solving their tax problems and giving them a clean exit. Use tools like Real Estate Radar to find these motivated owners before they ever hit the open market. This is how you win in a high-interest world.
The 'Big Three' Creative Strategies for Multifamily Success
Banks are middlemen. Using creative financing for multifamily properties lets you cut them out of the equation entirely. You're no longer begging a loan officer for a favor; you're offering a sophisticated solution to a property owner. By mastering these three strategies, you move from the slow lane of traditional lending into the high-speed world of strategic acquisition. Here is how you structure deals that win in 2026.
Seller Financing: The Win-Win Blueprint
Seller financing is the gold standard of creative deals. In this scenario, the seller becomes the bank. You and the owner agree on a purchase price and an interest rate. Instead of sending a check to a massive corporation, you pay the seller directly. The seller gets a higher total price and a steady stream of interest income without the headaches of daily management. You get the building without the 12% bank interest rates or the 25% down payment hurdles.
The legal structure is simple. The Note is your written promise to pay the debt. The Deed of Trust is the security instrument that protects the seller if you default. Consider the difference in where your money goes:
- Bank Interest: Capital leaves the deal forever to fund a bank's bottom line.
- Seller Interest: Capital stays between you and the owner, often creating a more flexible and affordable debt structure.
Master Lease Options: Control Without Ownership
Think of the Master Lease Option (MLO) as the ultimate test drive of multifamily investing. You lease the entire building from the owner for a set monthly amount. You manage the property, fill the vacancies, and raise the rents. You keep the "spread" between your lease payment and the property’s Net Operating Income (NOI). This is immediate cash flow without needing a title transfer or a massive loan.
The "Option" portion is where the real wealth is built. You lock in today’s purchase price for a future date, usually 3 to 5 years away. While FHA loans for multifamily properties require mountains of paperwork and strict property standards upfront, an MLO lets you take control today. You use the lease period to increase the property value, then exercise your option to buy once the asset is worth significantly more than your locked-in price.
Sometimes, a single strategy isn't enough to solve a seller's problem. You might create a Hybrid Deal by combining an MLO with a future seller-financed buyout. This flexibility is your superpower in a tight market. If you want to see the exact blueprints we use to structure these deals, our Mentorship Program walks you through every step of the process. Mastering creative financing for multifamily properties is about becoming a problem solver who can pivot when the bank says no.
Analyzing Creative Deals: How to Spot a 'Yes' From a Seller
Luck is not a strategy. Finding the perfect deal requires a systematic approach to identifying human problems that real estate can solve. Most investors fail because they only look at the bricks and mortar. To master creative financing for multifamily properties, you must look at the person behind the deed. You're looking for a "Fatigued Landlord" who is ready to trade their management headaches for a steady, passive income stream.
The Psychology of a Motivated Seller
A motivated seller isn't necessarily desperate; they're often just finished. They've reached a point where the asset has become a burden. When you offer creative terms, you're providing an exit ramp that a bank simply cannot build. You're offering them a "Seller's ROI," which is the total value of the deal plus the peace of mind of walking away. Look for these three specific pain points:
- Management Burnout: They've spent decades dealing with tenants, toilets, and trash. They want the income without the phone calls.
- Partnership Disputes: Business partners or heirs often have conflicting goals. A creative structure can provide the liquidity needed to settle the score.
- Looming Tax Bills: A cash sale can trigger a massive tax hit from capital gains and depreciation recapture. Creative terms allow them to spread that liability over several years.
The "Tax Hit" strategy is your most powerful negotiation tool. By accepting payments over time, the seller keeps more money in their pocket instead of handing a 20% to 37% chunk to the IRS. You're not just buying a building; you're providing a tax-advantaged retirement plan.
Crunching the Numbers on Non-Traditional Terms
When you use creative financing for multifamily properties, your Cash-on-Cash return can skyrocket. Because your upfront capital is significantly lower than a traditional 25% down payment, every dollar of profit works harder for you. However, you must ensure the property’s Net Operating Income (NOI) comfortably covers your debt service while still providing a cash-flow cushion.
Don't ignore the "Balloon Payment." Most creative deals include a date where the full balance becomes due, typically in 5 to 10 years. You must have a clear plan to refinance or sell before that deadline hits. Never guess on your math. Use the Multifamily Tool Kit to run your deal scenarios through professional calculators that account for these specific variables.
Stop wasting time on low-probability leads. Use Real Estate Radar to filter for owners with high equity and long-term ownership. These are the candidates most likely to accept terms. This software is your shortcut to finding the "Yes" in a crowded market.
The 90-Day Action Plan: Pitching and Closing Your First Deal
Execution is the only thing that separates a dreamer from a deal-maker. You don't need years of saving to find your first building. You need a system that moves at the speed of the market. This 90-day plan is designed to cut through the noise and put you in control of an asset while your competitors are still waiting for a lender's return call. Success requires movement, not meditation.
Start with Step 1: Build your target list. Use Real Estate Radar to pull off-market data on multifamily buildings. Filter for owners who have held their property for 10 years or more. These individuals typically have the most equity and the highest probability of accepting creative financing for multifamily properties. Step 2 is outreach. Don't pitch yet. Ask questions to find the pain. Is management burning them out? Are they worried about the tax bill from a sale? Listen more than you speak.
Step 3 is the "Two Offer" method. Present a lower cash offer alongside a higher terms-based offer. When sellers see they can get their full asking price by acting as the bank, the conversation shifts instantly. Step 4 involves due diligence. Verify the rent rolls and expenses to ensure the income is real. Step 5 is the close. This is where you sign the note and take control. You can achieve this entire cycle in under 90 days if you follow the framework.
The Script: How to Propose Creative Terms
Your words determine your wealth. Never start a conversation by saying you don't have the cash. Instead, frame the deal as a financial win for the owner. Use this 3-sentence approach: "I want to help you maximize your net proceeds from this sale without a massive tax hit. If I can meet your full asking price through a structured payment plan, would you be open to discussing terms? This gives you a steady monthly income while I take over the management burden."
If they demand all their cash now, point to the IRS. Explain that a lump sum triggers immediate capital gains and depreciation recapture. Show them how they'll actually keep more money over time by becoming the bank. You aren't asking for a favor; you're offering a sophisticated tax strategy.
Legal Guardrails and Due Diligence
Protect your empire. You must work with a real estate attorney who specifically understands creative finance. Standard boilerplate contracts won't work here. You need to address "Due on Sale" clauses and "Substitution of Collateral" to keep your deal secure. Beginner mistakes in legal paperwork can cost you everything you've built. Stop guessing and start following a proven blueprint. If you want to skip the trial and error, apply for our Mentorship Program today and get the exact tools you need to close.
Master the Art of the Deal with Multifamily Schooled
DIY is a dangerous trap in the world of high-stakes real estate. 95% of investors who try to go it alone fail because they get paralyzed by the complexity of creative financing for multifamily properties. They second-guess their numbers or freeze when a seller asks a tough question. You don't have to be part of that statistic. The 5% who succeed do so because they refuse to guess. They follow a battle-tested blueprint that removes the friction from every deal.
Our ecosystem is built on speed and certainty. We move you through a strategic pipeline, from our high-impact Online Challenges to our comprehensive 90-day system. This isn't just theory; it's a practical, results-driven journey. You gain access to the same frameworks used by the industry's top players to scale without bank interference. We provide the roadmap, the software, and the community to ensure you never walk into a negotiation alone.
Why a Mentor is Non-Negotiable for Creative Deals
When you're pitching a multi-million dollar asset, the seller needs to know you can perform. A mentor provides the instant credibility you might lack as a new investor. Within our Mentorship Program, we don't just teach you the steps; we help you execute them. We review your creative term sheets before you send them to an owner. We make sure your offers are bulletproof and your downside is protected. Success is a system, not a secret.
Immediate Action: The 5-Day Challenge
You need to sharpen your skills before you step into the arena. Our 5-Day Challenge prepares you for the "Big Three" strategies we've discussed. You'll learn to spot motivated sellers and structure win-win terms in a high-energy environment. You aren't just learning; you're joining a community of high-achievers who refuse to let 2026 interest rates stop their progress. This is where your transformation from a spectator to an owner begins.
The market in 2026 waits for no one. You can either watch from the sidelines or take control of your financial future today. Join the movement and start building your multifamily empire with the right support system behind you. Get the tools and training you need to win and secure your first asset in the next 90 days. Your journey to passive income and equity starts with a single, decisive action.
Build Your Multifamily Empire Today
The 2026 market doesn't reward the hesitant. You now have the blueprint to bypass restrictive bank lending and high interest rates. By mastering creative financing for multifamily properties, you've shifted from a borrower to a strategic problem solver. You can now identify fatigued landlords, structure win-win terms, and secure cash-flowing assets that others think are impossible to fund. Success isn't a secret; it's a proven system that favors the bold.
Don't let this knowledge sit idle while opportunities pass you by. You need the right tools and expert guidance to execute at a high level. Our proprietary Deal Finding Software and multi-generational mentorship provide the shortcut you've been looking for. We're so confident in this framework that we guarantee the results. You will find a deal in 90 days or we'll provide one for you. This is your moment to stop dreaming and start owning.
Start Your 90-Day Multifamily Journey Now. The path to long-term independence and asset accumulation is right in front of you. Take the first step toward your new life today.
Frequently Asked Questions
Is creative financing for multifamily properties legal?
Yes, creative financing is perfectly legal and has been used in real estate for decades. It involves standard legal instruments like promissory notes and deeds of trust. You aren't bypassing the law; you're simply bypassing the bank's rigid lending requirements. It's vital to work with an attorney who understands these specific structures to ensure your contracts comply with state regulations. These strategies allow for private, flexible agreements between a buyer and a seller.
How much money do I actually need to start with creative financing?
You don't need a 20% or 25% down payment like traditional banks require. While "no money down" is possible, most creative deals require some entry capital for earnest money or a smaller seller down payment. The amount depends entirely on your negotiation skills and the seller's specific needs. Many investors use creative financing for multifamily properties to control assets with significantly less cash out of pocket than a standard mortgage would ever demand.
What happens if a seller says they only want a cash offer?
You should present the "Two Offer" method to show them the financial benefits of terms. Explain how a cash offer triggers immediate capital gains taxes. Show them that by acting as the bank, they receive a higher total purchase price and steady interest income. Most sellers who insist on cash simply don't understand the tax advantages. Providing a side-by-side comparison often shifts their perspective from wanting a lump sum to wanting long-term wealth.
Can I use creative financing for properties with existing mortgages?
Yes, you can use "Subject-To" or "Wraparound Mortgages" to handle properties with existing debt. These methods allow you to take over the seller's payments while the original loan stays in place. You must be aware of "Due on Sale" clauses, which give banks the right to call a loan due if the title transfers. Professional mentorship is essential to navigate these specific legal hurdles without triggering bank interference or risking your investment.
What is the difference between a Master Lease Option and Seller Financing?
A Master Lease Option gives you control without immediate ownership. You lease the property and have an option to buy it later at a fixed price. Seller Financing involves an actual transfer of the title where the seller holds a promissory note for the debt. Use a Master Lease when the seller isn't ready to sell or has a mortgage that prevents a clean title transfer at this exact moment.
How do I find sellers who are open to creative terms?
You find them by targeting off-market properties held by individuals rather than large corporations. Look for "Fatigued Landlords" who have owned their buildings for 10 or more years. These owners often have high equity and a desire to retire from active management. Using specialized Deal Finding Software allows you to filter for these high-probability candidates and reach out to them before they ever list with a traditional broker.
Do I need a high credit score to use seller financing?
No, your personal credit score is rarely a factor in creative financing. Because the seller is the bank, they decide the lending criteria. They are usually more interested in your track record, your down payment, and your plan to manage the asset effectively. Creative financing for multifamily properties is the ultimate equalizer for investors who have the skills but lack the perfect credit profile required by traditional institutional lenders in 2026.
What are the biggest risks of creative real estate investing?
The primary risks include "Due on Sale" clauses, balloon payments, and poor property management. If you don't have a plan to refinance before a balloon payment is due, you could lose the asset. You must also ensure the property’s cash flow covers the debt service with a safety margin. Following a proven framework and having expert mentorship helps you identify these risks early and build legal guardrails into your contracts to protect your equity.



