
Creative Financing for Multifamily Properties: The 2026 Investor Blueprint
Stop waiting for interest rates to drop or for banks to loosen their grip on your dreams. If you're still trying to save up a massive down payment for every deal, you're playing a losing game in this market. The most successful investors right now aren't using their own cash. They're mastering creative financing for multifamily properties to bypass traditional hurdles entirely.
You probably feel the weight of restrictive lending requirements and the constant fear of running out of personal capital before you hit your goals. It's a common trap that keeps most people stuck in small residential units. I'm going to show you how to break free and acquire 5+ unit properties using elite strategies that turn a bank's "no" into a closed deal.
This is your 2026 investor blueprint for rapid scaling. We'll cover exactly how to pitch sellers on creative terms, manage the new FinCEN reporting rules for non-traditional transfers, and use leverage to build a massive portfolio without relying on a single bank. Get ready to transform your financial future and take control of your legacy today.
Key Takeaways
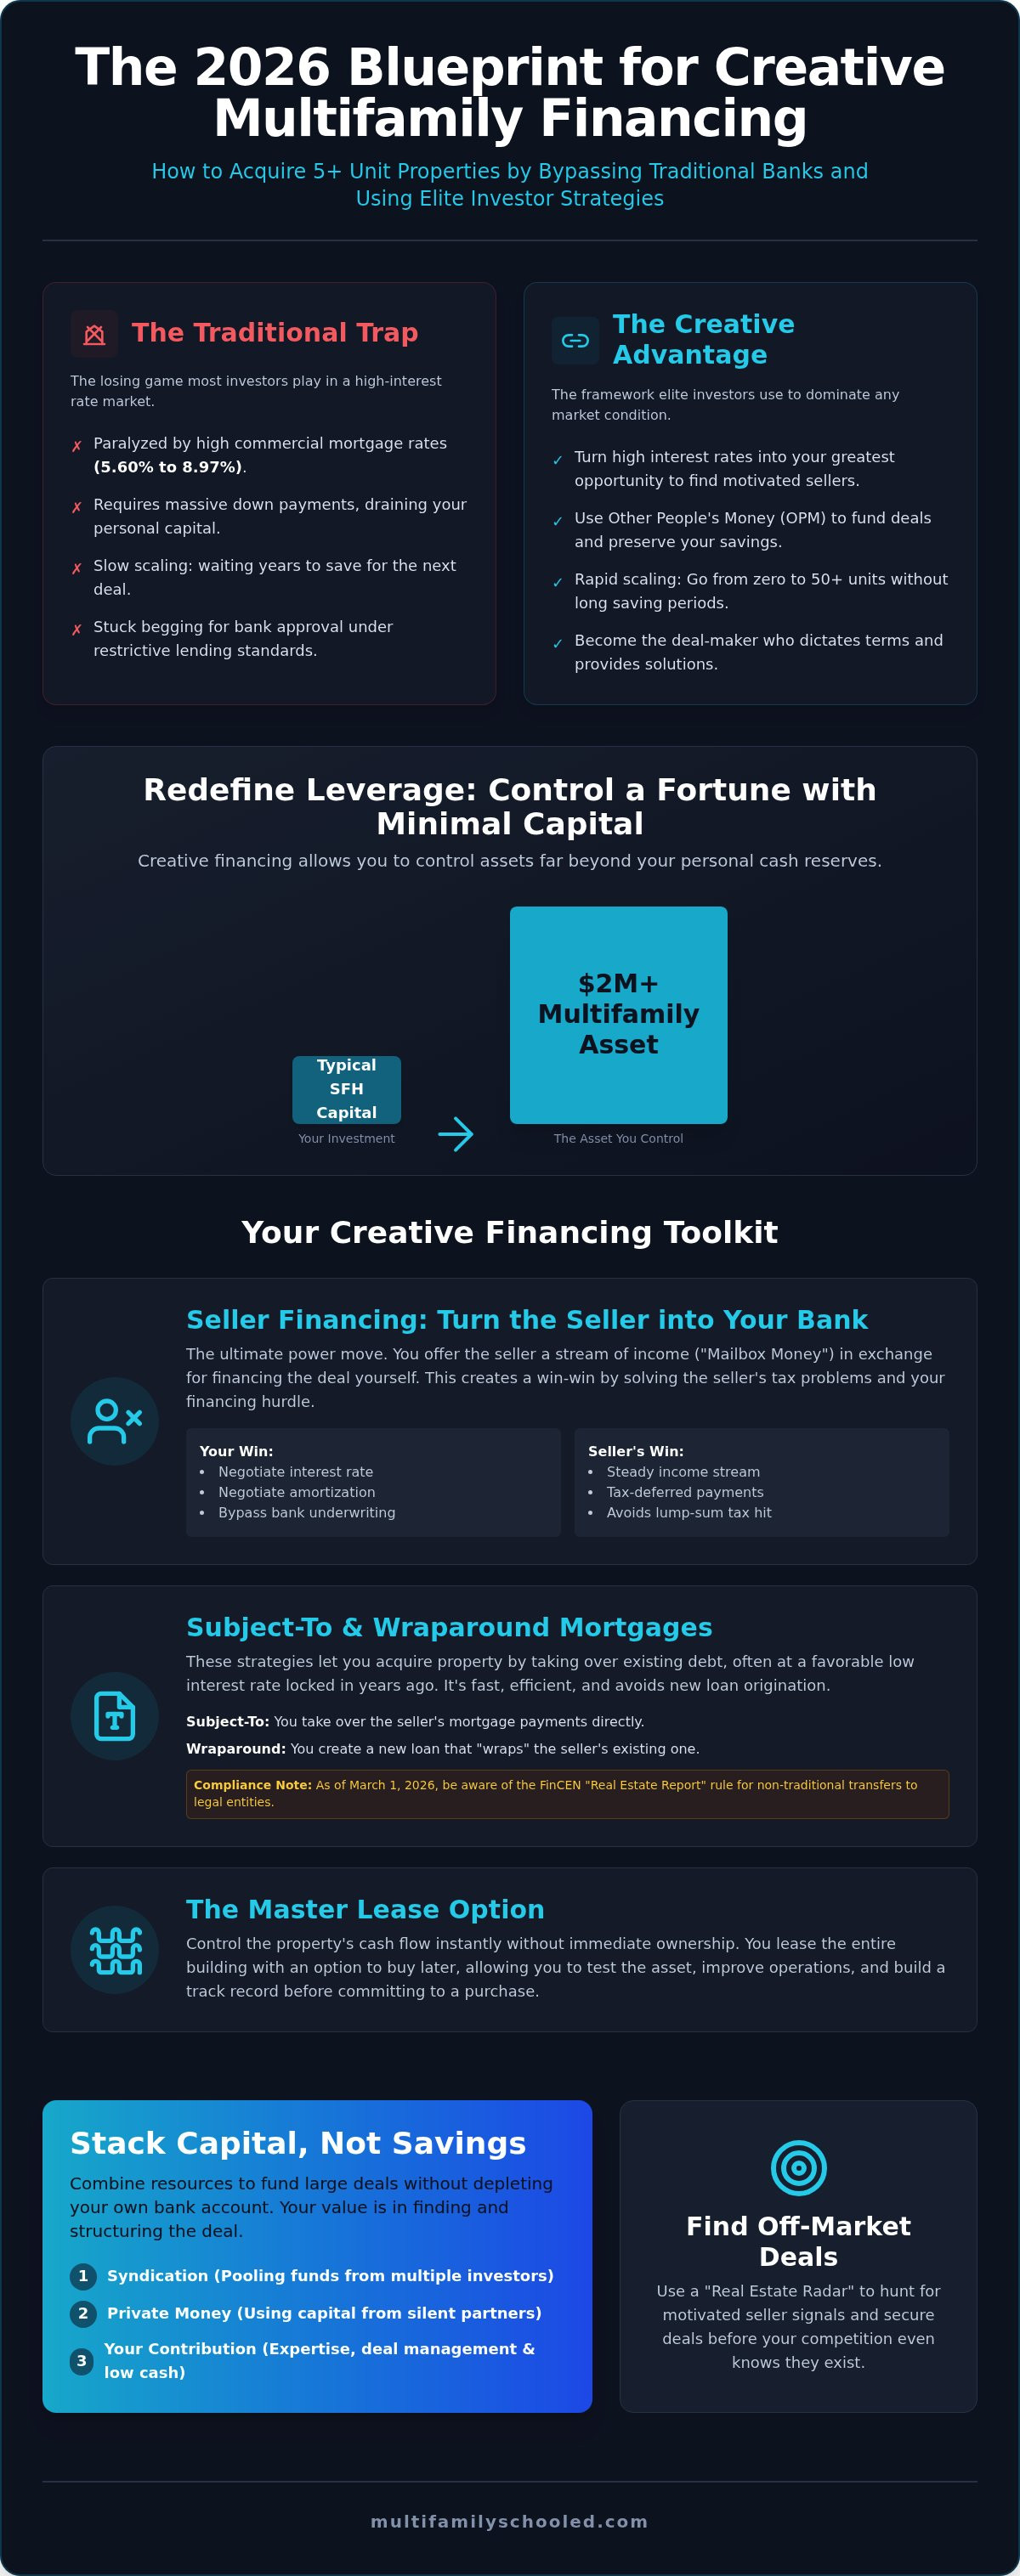
- Learn how to control $2M+ assets with the capital of a single-family home by redefining leverage in the 2026 market.
- Master the Carry-Back and Master Lease Options to turn sellers into your private bank and control cash flow instantly.
- Discover how to stack capital using syndication and silent partners to fund deals without depleting your own savings.
- Use Real Estate Radar to hunt for motivated seller signals and secure off-market deals before your competition even knows they exist.
- Secure your financial future by mastering creative financing for multifamily properties and acquiring your first 5+ unit building in just 90 days.
The Power of Creative Financing: Why Apartments are Your 2026 Wealth Vehicle
High interest rates are your greatest opportunity. While others complain about commercial mortgage rates ranging from 5.60% to 8.97%, you'll see a market ripe for the taking. Traditional banks are paralyzed by the 7.3% national rental vacancy rate and tightening lending standards. This is where you step in. You don't need a massive war chest to win. You need the right strategy. Stop playing by the old rules and start using the tools that elite investors use to dominate the field.
Imagine controlling a $2 million asset with the same capital most people waste on a single-family home. That's the power of creative financing for multifamily properties. By using Other People's Money (OPM), you increase the velocity of your capital. You can scale from zero to 50 units in record time because you aren't waiting years to save for the next down payment. Traditional financing feels like a cage; creative structures are the key to the lock. You're moving from the slow lane of saving to the fast lane of acquiring. It's about wealth, not just income. Creative debt structures prioritize long-term asset accumulation that outlasts any temporary market dip.
The "No Money Down" Myth vs. Reality
Let's be real. "No money down" is often a marketing slogan. In the world of serious 5+ unit deals, "low money down" is the professional standard. You might trade a slice of equity for a partner's cash or offer your expertise to manage a complex turnaround. Creative financing techniques allow you to stop being a humble borrower begging for a bank's approval. You become the deal-maker. You dictate the terms. It's a psychological shift from asking for permission to providing a solution for a motivated seller. When you bring the deal and the expertise, the cash will follow. Stop worrying about your bank balance and start focusing on your deal-flow.
Multifamily Scalability in 2026
Why hunt for 50 units under one roof? It's infinitely more efficient than managing 50 separate houses. Commercial financing is based on Net Operating Income (NOI), not just your personal credit score. If you increase the income of a building, you increase its value. In August 2026, we're in a "Golden Window." High supply and slowing rent growth mean sellers are facing headwinds they didn't expect. The federal funds rate sitting between 3.50% and 3.75% has changed the landscape for everyone. Sellers are more likely to accept creative terms to move an asset that's no longer performing for them. Don't wait for the perfect moment; create it using a systematic, proven framework. Build a legacy that provides long-term independence starting today.
The Creative Financing Toolkit: Seller Financing, Master Leases, and Subject-To
Stop viewing the bank as your only path to a closing. You have a toolkit that makes you the most flexible buyer in the room. When traditional lenders tighten their requirements, you win by offering solutions they can't match. Creative financing solutions have become the standard for savvy investors who refuse to let high interest rates or capital shortages stop their momentum. By understanding these instruments, you stop being a borrower and start being a strategist.
Subject-To and Wraparound Mortgages are your weapons for acquiring debt already in place. In a "Subject-To" deal, you take over the seller’s existing low-interest mortgage payments. It's fast, efficient, and keeps the original financing terms intact. A Wraparound Mortgage goes a step further. You create a new note that "wraps" around the original debt, allowing you to pay the seller while they continue to pay their lender. Be aware that as of March 1, 2026, the FinCEN reporting rule requires a "Real Estate Report" for these non-traditional transfers to legal entities. This transparency is now part of the game, but it doesn't slow down a pro who knows the rules.
Mastering Seller Financing
Turning the property owner into your private bank is the ultimate power move. You aren't just buying a building; you're offering the seller "Mailbox Money." Many owners of 5 to 50-unit properties want to retire but fear the massive tax hit of a lump-sum sale. By carrying the note, they receive tax-deferred income and a steady interest rate that likely beats their savings account. You get to negotiate the interest rate, the amortization schedule, and the balloon payment. It's a win-win scenario that secures your asset while solving the seller’s liquidity and tax problems simultaneously.
The Master Lease Strategy
The Master Lease Option (MLO) is the ultimate "test-drive" for creative financing for multifamily properties. You take over the management and cash flow without an immediate title transfer. This allows you to use your expertise to increase the Net Operating Income (NOI) through forced appreciation. Once you've boosted the property's value, you'll have the equity needed to secure better bank financing later. You're locking in today’s purchase price for tomorrow’s higher value. If you want to see how these tools fit into a larger strategy, consider joining our Mentorship Program to refine your pitch. This strategy minimizes your entry risk while maximizing your long-term wealth potential.
Creative Capital Stacking: Syndication and Private Money
You've identified a prime deal. Now you need the fuel to close it. Capital stacking is the high-level art of layering different funding sources to minimize your personal out-of-pocket expense. In 2026, traditional banks often demand a 20% to 30% down payment for commercial assets. That's a massive barrier for most, but it doesn't have to stop you. You solve this by bringing in "Silent Partners" or equity partners who provide the cash in exchange for a piece of the equity. It's a strategic trade. You give them passive returns; they give you the leverage to control a multi-million dollar asset. This is a core pillar of creative financing for multifamily properties.
Syndication is how you scale from small buildings to massive complexes. It's the process of pooling capital from multiple investors to take down deals you couldn't afford alone. While institutional players are currently limiting their exposure, you can move faster by using private money. Private money comes from individuals looking for better returns than a savings account, whereas hard money comes from specialized lending companies. Private money is usually cheaper and far more flexible. Use these creative financing solutions to bridge the "gap" between what the bank offers and what the seller requires. You aren't just a buyer; you're a capital architect.
The Basics of Raising Capital
Pitching isn't about begging for money. It's about sharing a vision of economic empowerment. You're offering investors a way to escape market volatility by owning a tangible, income-producing asset. In a typical syndication, you'll use a GP/LP split. As the General Partner (GP), you manage the property and the strategy. The Limited Partners (LPs) provide the funds and enjoy passive income. Compliance is vital. Most syndications fall under SEC Regulation D, which generally requires investors to be "accredited." This means they must have a net worth over $1 million or a specific annual income. Don't guess on the legalities; build your business on a foundation of certainty and professional ethics.
Finding Private Lenders
The money you need is likely hiding in plain sight within your own network. In 2026, local professionals like doctors, lawyers, and business owners are desperately looking for stability. They have the capital but lack the time to find and manage apartment buildings. You provide the solution they've been waiting for. If you're working on your first deal, you must project absolute authority. Use the Multifamily Tool Kit to present professional, data-backed numbers that command respect from day one. You don't need a 20-year track record if you have a rock-solid deal and a systematic approach to creative financing for multifamily properties. Start networking today and watch your portfolio explode.
The 90-Day Deal-Finding Roadmap: Hunting for Creative Opportunities
Stop waiting for the perfect deal to land in your inbox. In 2026, the best opportunities are off-market and invisible to the average investor. You need a systematic roadmap to uncover creative financing for multifamily properties before your competition even knows they exist. This isn't about luck. It's about data-driven hunting and aggressive outreach. You can find, analyze, and secure a property in 90 days if you follow this blueprint. Success favors the proactive.
Your first step is identifying signals of a motivated seller. Look for high equity, long-term ownership of ten years or more, and out-of-state addresses. These owners often feel the burden of management without the energy to fix problems. Instead of manual searching, use Real Estate Radar to filter these leads instantly. This software does the heavy lifting, allowing you to focus on the conversation rather than the spreadsheet. Once you have the data, move to direct outreach. Craft an offer that focuses on the seller's needs, not just your own. Finally, perform a cold analysis. Ensure the creative terms don't kill the cash flow. You're building a wealth vehicle, not a liability.
Filtering for Success
Target "Mom and Pop" owners specifically. These individuals are ten times more likely to consider seller financing because they value steady income over a massive tax bill. Distinguish between a distressed property and a distressed owner. A building might be in great shape, but if the owner is tired of managing tenants, they are ready for a creative exit. Use data to predict who needs a Master Lease solution based on high vacancy rates or deferred maintenance. You're looking for the gap between the property's current performance and its true potential. That gap is your profit margin.
The Pitch: Scripting Your Win
The pitch is where the deal is won or lost. Ask the Golden Question: "If I could give you your price, could you give me my terms?" This shifts the focus from a battle over dollars to a partnership on structure. Explain the tax benefits clearly. Many non-pros don't realize a seller carry-back allows them to defer capital gains taxes over several years. When they say they want all their cash now, remind them of the current interest rate environment. They can earn a higher interest rate from you than they can from a bank deposit. You're solving their problem while securing your asset. If you want a proven system to guide your outreach, join our Mentorship Program and let us help you close your first 5+ unit deal. Start your 90-day roadmap today.
The Mentorship Advantage: Secure Your Deal with Multifamily Schooled
Why do 90% of deals involving creative financing for multifamily properties fall apart? Most of them die at the closing table. Inexperienced investors lack the framework to handle complex paperwork. They fail to soothe a seller's last-minute anxiety. You can't afford to guess when millions are on the line. The cost of waiting in 2026 is too high. Traditional lending is restrictive. You need a system that bypasses these hurdles and forces a result. Don't let your ambitions stall because you lack a proven roadmap. Success in this market requires more than just knowledge; it requires a tactical advantage.
Our Mentorship Program provides the ultimate "done-with-you" solution. We back this with a bold 90-day deal guarantee. If you follow the system and don't secure a deal, we'll find one for you. This removes the paralyzing fear of failure. It places you inside an "Inner Circle" of private lenders and elite creative deal-makers. You're no longer alone in the wilderness. You're part of a fast-moving, successful movement designed for economic empowerment and long-term independence. We provide the tools for a guaranteed path to success.
Your Fast-Track to Mastery
Start your journey with the 5-Day Multifamily Challenge. This is the entry point to building your foundation. You'll learn Justin Brennan’s proprietary methodology. It's built on a multi-generational industry heritage and real-world expertise. This isn't theoretical guesswork. It's a strategic blueprint for navigating the 2026 financing landscape. We simplify complex professional concepts into branded, manageable packages. You'll stop being a spectator. You'll start being a high-energy owner. Seize this opportunity before the market shifts again.
Next Steps for the Action-Oriented Investor
Success requires immediate, decisive action. Download the Multifamily Tool Kit right now to begin your analysis. This tool ensures your numbers are professional and command respect from sellers and partners alike. Audit your local market using Real Estate Radar to find the off-market leads others miss. Commit to the 90-day timeline. Your first apartment building isn't a distant dream. It's a scheduled milestone on your path to prosperity. Take the first step today and secure your future. The time to scale is now.
Take Command of Your Multifamily Future Today
The 2026 market doesn't wait for the hesitant. You've seen the blueprint. You now understand that creative financing for multifamily properties isn't just a backup plan. It's your primary weapon for scaling rapidly in a high-interest environment. By mastering seller carry-backs, master leases, and strategic capital stacking, you're no longer at the mercy of restrictive bank requirements. You're a sophisticated deal-maker with the exact tools needed to build a lasting legacy. Stop overthinking and start executing.
You have immediate access to our proprietary Real Estate Radar AI software to filter the best off-market leads. You're backed by A-Z training from multi-generational experts who've mastered every market cycle. This isn't just theory. It's a proven, systematic framework supported by our bold 90-Day Deal Guarantee. If you're ready to stop trading your time for a paycheck and start accumulating generational assets, the path is wide open. Your first 5+ unit building is waiting for you to claim it.
Find Your First Deal in 90 Days—Join the Mentorship Program Now!
Frequently Asked Questions
Is creative financing legal for commercial multifamily properties?
Creative financing for multifamily properties is entirely legal and governed by standard contract law. You're simply negotiating private terms between two parties instead of following a bank's rigid rulebook. It's vital to have a real estate attorney review your documents to ensure compliance with state regulations. As long as your contracts are transparent and signed by all parties, you can legally structure deals that bypass traditional lending hurdles and accelerate your path to ownership.
How much down payment do I really need for seller financing?
Down payments for seller-financed deals are completely negotiable and often fall between 5% and 10%. This is a massive advantage compared to the 25% or 30% usually required by commercial banks. Your goal is to find a seller's specific pain point. If they need immediate liquidity, you might pay more upfront. If they want to defer taxes, you can often secure the asset with very little cash out of pocket today.
Can I use creative financing if I have a low credit score?
Yes, you can successfully use these strategies regardless of your personal credit score. Sellers are primarily interested in the property’s Net Operating Income and your plan to protect their equity. In many cases, the seller never even runs a credit check because they hold the deed as collateral. If you stop paying, they simply take the building back. Focus on presenting a professional business plan rather than worrying about your FICO score.
What is the "Subject-To" strategy and is it risky?
The Subject-To strategy involves taking over a seller’s existing mortgage payments while keeping the original loan in place. The primary risk is the "due on sale" clause, which allows a bank to demand full repayment if the title transfers. While this is rare in a performing loan environment, you must have a backup plan. Successful investors mitigate this risk by maintaining strong cash reserves and ensuring the property stays profitable enough to refinance if necessary.
How do I find sellers who are willing to finance the deal themselves?
You find these sellers by targeting "Mom and Pop" owners who have high equity and long-term ownership. These individuals are often tired of the three Ts: tenants, toilets, and trash. Use data-driven software like Real Estate Radar to filter for out-of-state owners or properties with deferred maintenance. Direct outreach is the key. When you offer a solution that provides steady income without management headaches, sellers are often eager to finance the deal.
What are the tax benefits of seller financing for the person selling the building?
Sellers enjoy significant tax advantages through what the IRS calls an installment sale. Instead of paying a massive capital gains tax on the full purchase price in year one, they spread the liability over the life of the loan. This often keeps them in a lower tax bracket and provides a higher interest rate than a traditional savings account. It's a powerful pitch that turns a simple sale into a long-term wealth strategy for the seller.
Do I need a lawyer to structure a Master Lease Option?
You absolutely need a qualified real estate attorney to draft and review your Master Lease Option. This is a complex legal instrument that separates the right to use and manage the property from the actual title. A lawyer ensures that your option to buy is protected and that the seller cannot sell the building to someone else while you're improving it. Don't cut corners on legal protection when you're building a multi-million dollar portfolio.
How does creative financing work with existing bank loans?
Creative financing for multifamily properties often works alongside existing debt through wraparound mortgages or second liens. You create a new note that "wraps" around the seller’s current bank loan, allowing you to make one payment to the seller while they continue paying the bank. It requires transparency and careful coordination to ensure the original lender remains satisfied. When structured correctly, it's a seamless way to acquire properties without needing to originate a new, high-interest commercial loan.



