
1031 Exchange Into Multifamily: Direct Ownership, DSTs, and the Key Rules
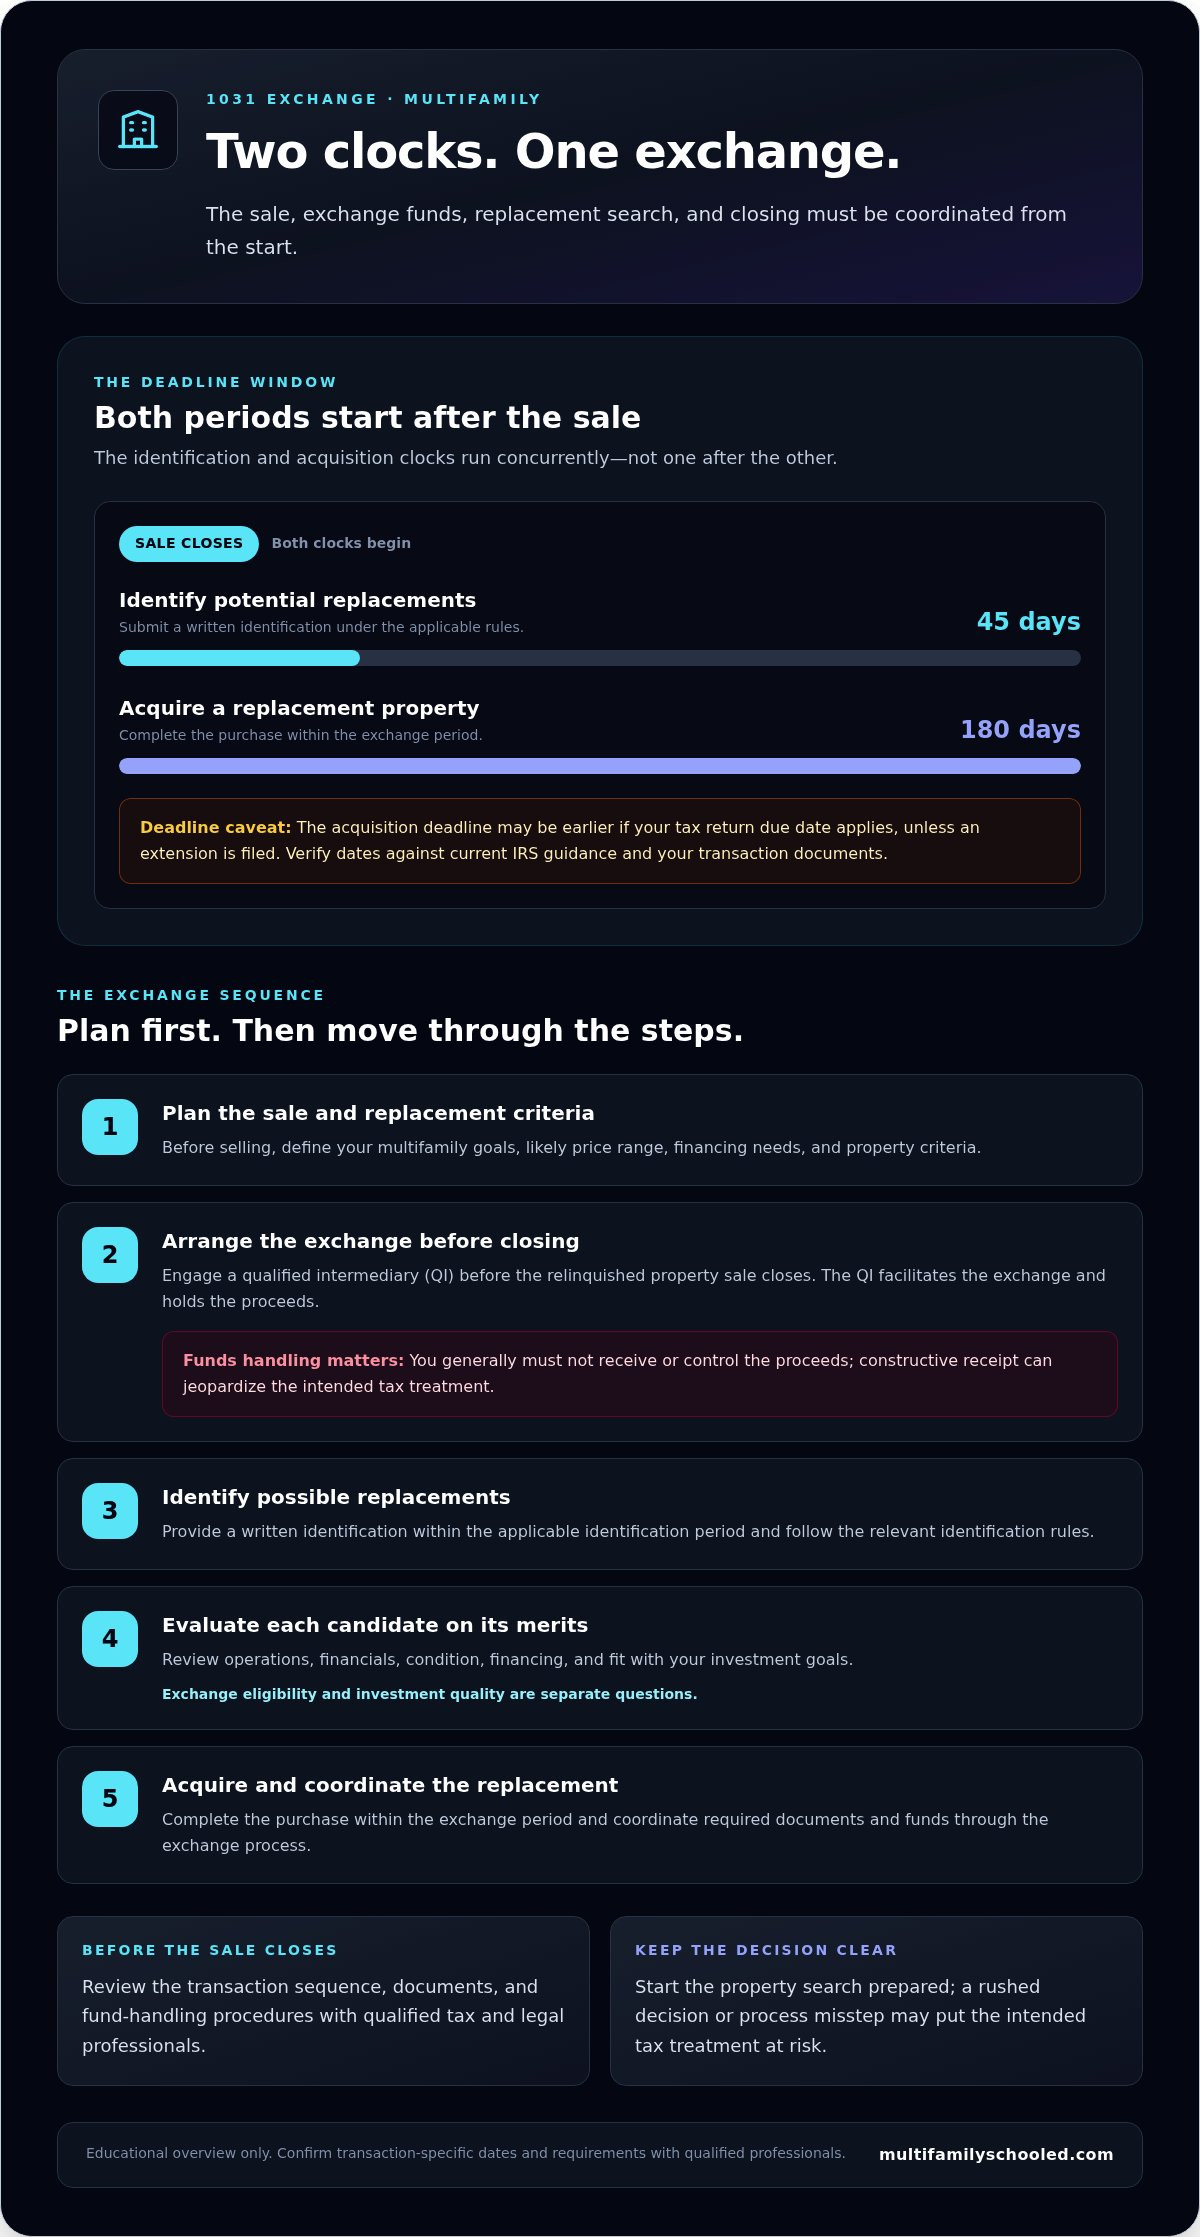
The biggest 1031 exchange mistake may be choosing a multifamily deal before understanding the clock. A 1031 exchange into multifamily is a timed property decision, not just a tax-deferral tactic. You have 45 days after selling your relinquished property to identify potential replacements and 180 days to complete the exchange. Both deadlines run at the same time.
If you’re considering the move, it’s natural to focus on preserving tax deferral while finding a property that fits your goals. But qualifying real estate, tight deadlines, and the handling of exchange funds all matter. A process misstep can put the intended tax treatment at risk, so plan your next move early.
This guide explains the exchange sequence and timing rules, then compares direct apartment ownership with investing through a Delaware Statutory Trust (DST). You’ll also find practical considerations for control, management, and due diligence. Understand the process first, then decide which route fits your investment goals and preferred level of involvement.
Key Takeaways
- A 1031 exchange defers tax rather than eliminating it, and the real estate involved must meet eligibility rules.
- Understand how the exchange moves from sale planning to identifying and acquiring a replacement property, including the qualified intermediary’s role.
- Compare direct ownership and a DST by weighing operational involvement, decision-making, diversification, liquidity, and due diligence.
- Use a preparation checklist to align your 1031 exchange into multifamily with your investment goals, capital needs, risk tolerance, and management preferences.
- Keep property underwriting separate from exchange compliance. Tax deferral doesn’t remove investment or execution risks.
What Does a 1031 Exchange Into Multifamily Actually Mean?
In plain English, a Section 1031 exchange lets an investor defer recognition of gain when exchanging qualifying real property held for investment or productive use in a trade or business for other qualifying real property of like kind. “Like kind” broadly describes the nature or character of the real estate, not whether the two properties are identical. For a foundational overview of the rule, see Internal Revenue Code section 1031.
A 1031 exchange into multifamily can mean replacing qualifying real estate with an apartment property owned directly, or with a Delaware Statutory Trust (DST) interest if the structure and transaction meet the applicable requirements. The potential benefit is tax deferral, not tax elimination. Tax may be due when the replacement property is eventually sold without another qualifying exchange. Not every sale, property, or investor situation qualifies.
Which property and investor situations may fit?
The general context is real estate held for investment or business use. A property used personally, such as a primary residence, doesn’t automatically meet that standard. Mixed personal and investment use can require closer analysis. The replacement property is the qualifying real estate acquired through the exchange. For example, an investor selling an eligible rental property might acquire an apartment building as the replacement, subject to current rules and the details of the transaction.
What is a Delaware Statutory Trust investment?
A DST is a legal ownership structure that can hold real estate for investors. Instead of buying and operating an entire apartment property directly, an investor acquires a beneficial interest in the trust. Under IRS Revenue Ruling 2004-86, a qualifying DST interest may be treated as an interest in real property for Section 1031 purposes. That treatment depends on the trust and the exchange meeting applicable requirements.
DST ownership is generally passive. Investors don’t directly operate the underlying apartment property or make its day-to-day management decisions. Direct ownership, by contrast, usually involves more operational responsibility, though it doesn’t guarantee control over every decision. The right route depends on your goals, desired involvement, and comfort with the specific investment structure.
This overview is educational, not tax or legal advice. Section 1031 eligibility and the treatment of a DST depend on the facts, documentation, and rules applicable to the specific transaction. Before acting, have qualified tax and legal professionals review your circumstances. Assess the property or trust on its investment merits as well as its potential exchange treatment.
How Does the 1031 Exchange Process Lead to Multifamily Property?
A successful 1031 exchange into multifamily depends on coordinating the sale, exchange funds, replacement-property search, and closing. Treat the timeline as part of the transaction from the start, not as paperwork to handle after a deal catches your eye.
- 1. Plan the sale. Define your multifamily goals, likely price range, financing needs, and property criteria before selling the relinquished property.
- 2. Arrange the exchange. Engage a qualified intermediary (QI) before the sale closes. The QI facilitates the exchange and holds the proceeds. The investor generally must not receive or control those funds, since constructive receipt can jeopardize the intended treatment.
- 3. Identify replacements. Submit a written identification of potential replacement properties within the applicable identification period, following the relevant identification rules.
- 4. Evaluate options. Review each candidate’s operations, financials, condition, financing, and fit with your investment goals. Exchange eligibility and investment quality are separate questions.
- 5. Acquire the replacement. Complete the purchase within the exchange period and coordinate required documents and funds through the exchange process.
What happens before the relinquished property sells?
The relinquished property is the investment or business-use real estate being sold. Exchange planning and QI arrangements generally need to be in place before closing because the exchange structure and handling of proceeds matter from the outset. Before the sale closes, review the transaction sequence, documents, and fund-handling procedures with qualified tax and legal professionals. Don’t assume you can sell first and set up an exchange afterward.
How do identification and acquisition deadlines work?
Under the standard federal timeline, you have 45 days after transferring the relinquished property to identify possible replacements and 180 days to acquire a replacement property. These periods run concurrently, not one after the other. The acquisition deadline may be earlier if your tax return due date applies, unless an extension is filed. Exact dates and counting can depend on the transaction, so verify them against current IRS guidance and your documents.
The search window is short. Set property criteria and financing expectations early so you can assess options without relying on a rushed decision. A multifamily investing toolkit can help organize property evaluation alongside exchange planning, but it can’t determine tax eligibility.
Missing a deadline or mishandling proceeds may jeopardize the intended tax treatment. Use this sequence as an educational overview, not as advice for calculating your specific dates or structuring your exchange. Prepare your multifamily criteria with the multifamily investing toolkit, then have qualified professionals review the rules that apply to your transaction.
Direct Multifamily Ownership vs. a DST: Which Trade-Offs Matter?
A 1031 exchange into multifamily can lead to two very different ownership experiences. Buying an apartment property directly puts you closer to its operations and decisions. A Delaware Statutory Trust (DST) offers a more passive interest in real estate, usually with less day-to-day involvement and less direct control. Neither route is automatically safer or more profitable. Match the structure to your goals, capacity, and risk tolerance.
| Factor | Direct multifamily ownership | DST interest |
|---|---|---|
| Control | You select the property and may influence asset-level decisions, subject to ownership agreements, lenders, and other partners. | The sponsor or trustee generally makes property decisions; investors have limited control over daily operations. |
| Management duties | Often requires active oversight of operations, financing, vendors, and property performance, whether handled personally or through hired management. | Generally more passive. The sponsor oversees the underlying property, with investor involvement defined by the offering documents. |
| Diversification | Investment is tied to the property or properties you acquire. Broader exposure may require multiple investments. | A DST may hold one or more properties, but diversification depends on the specific trust and offering. |
| Liquidity | Real estate can take time to sell, and a sale depends on market conditions and transaction requirements. | Interests are generally illiquid and may have limited transfer or exit options. |
| Due diligence | Assess the property, operations, financing, partners, and your capacity to oversee the investment. | Review the sponsor, property, leverage, fees, distribution assumptions, liquidity, and exit terms. |
What changes when you own an apartment property directly?
Direct ownership means evaluating the property and its operations, arranging financing, and deciding how to respond to asset-level needs. Your actual authority depends on the ownership structure, loan terms, and agreements with partners or managers. You also have direct exposure to the property’s performance and operational risks. Build your evaluation skills with this multifamily investing toolkit.
What should you understand before considering a DST?
In a DST, the sponsor typically manages the underlying property while investors hold beneficial interests. Review the offering documents closely. They explain the structure, sponsor’s role, fees, debt, projected distributions, transfer restrictions, and potential exit path. Assumptions aren’t guarantees, and DST terms can vary. Understand which decisions you give up and how limited liquidity could affect your plans before comparing a DST with direct ownership.
Use the comparison to clarify your preferences, not to label one path the winner. Ownership structure, property quality, sponsor execution, financing, and market conditions all shape risk. Keep those factors separate from whether a particular interest may qualify for exchange treatment.
How to Prepare for a Multifamily 1031 Exchange Without Rushing the Decision
A clear plan helps you compare investment options without letting the exchange clock make the decision for you. Separate two tasks from the start: underwrite the property or DST offering, and confirm that the exchange follows applicable tax rules. A deal calculator can help organize assumptions, but it can’t determine tax eligibility.
Set your multifamily investment criteria before identifying property
Write down your priorities before the search begins. Consider:
- Sale timing: Your anticipated closing date and the milestones that follow.
- Investment goals: The role you want the investment to play and your expected holding approach.
- Property criteria: Target geography, property size, and operating model.
- Capital needs: Available funds, financing capacity, and reserves for ownership or investment costs.
- Risk and involvement: Your tolerance for property-level uncertainty and appetite for active management.
For direct ownership, assess whether your financing capacity, reserves, and management plan fit the property. Review its operations, financials, condition, and financing. For a DST, review the sponsor and offering documents alongside the underlying real estate. Compare the stated assumptions, fees, debt, distribution expectations, liquidity restrictions, and exit terms. Details vary by offering, so a general comparison is no substitute for reviewing the specific investment.
Multifamily deal-finding software can help you explore apartment opportunities and organize your search. Use it to support property research, not to decide whether an exchange qualifies.
Build a timeline that respects the exchange deadlines
Work backward from the sale closing date. Allow time to refine your criteria, review candidate properties or offerings, assess financing, and examine documents before key exchange milestones. Under the standard timeline, the identification period is 45 days after the sale and the exchange period is 180 days. They run concurrently, so the acquisition window doesn’t begin after identification ends.
Keep your review process disciplined. Don’t choose an investment solely because a deadline is approaching. A property’s financial assumptions, condition, debt, and operating plan deserve careful review. A DST’s sponsor, offering structure, and exit provisions do too. If an option doesn’t meet your criteria, pressure doesn’t make it a better fit.
Before the sale, map the anticipated dates and responsibilities with qualified tax and legal professionals. Verify deadline calculations, exchange procedures, and transaction-specific requirements against current rules and documents. Multifamily education can also help you strengthen your evaluation process as you plan your next move.
Your Next Step: Turn 1031 Exchange Knowledge Into a Multifamily Plan
A 1031 exchange into multifamily involves more than finding a replacement property. Build your decision in order: understand the exchange rules, compare direct ownership with a DST, define your investment criteria, then verify how current rules apply to your transaction. Keep two questions separate throughout: “Does this investment fit my goals?” and “Does this transaction meet the exchange requirements?” A property can suit your investment strategy without qualifying for tax treatment, or meet exchange criteria without being the right investment for you.
Questions to answer before choosing a replacement-property path
- Direct ownership: Do you have the time, experience, and operating plan for the responsibilities that come with owning an apartment property? How do financing, partners, and management arrangements affect your role?
- DST ownership: Are you comfortable with limited control over the underlying property and potentially limited liquidity? Do the sponsor, offering terms, and investment structure fit your preferences?
- Exchange eligibility: Which tax and procedural rules apply to your specific sale and proposed replacement? This is distinct from evaluating the property’s operations, financial assumptions, or risks.
Neither route removes investment uncertainty. Market conditions, property performance, sponsor execution, liquidity constraints, and transaction timing can all affect the outcome. Read the relevant property or offering documents carefully, and make decisions based on the specific details rather than broad assumptions about a structure or its potential tax treatment.
Keep learning while protecting the decision
Build your ability to assess multifamily operations, analyze property information, and compare investment structures before a deadline forces a choice. Multifamily education and mentorship can help you develop a more systematic approach to evaluating opportunities. They don’t replace transaction-specific tax or legal advice, determine exchange qualification, or guarantee investment returns or a successful acquisition.
Start with one practical step: write down your ownership preferences, investment criteria, and unanswered exchange questions. Use those notes to guide your research and discussions with qualified tax and legal professionals. For structured support as you build your multifamily investing knowledge, explore multifamily investing mentorship.
Build Your Multifamily Plan With Confidence
A 1031 exchange into multifamily starts with understanding the exchange rules, then choosing a replacement-property path that fits your goals. Direct ownership can bring greater operational involvement, while a DST generally offers a more passive role with limited control and liquidity. Neither option removes investment risk, and tax eligibility is separate from deciding whether a property or offering suits you.
Set your criteria early, examine the actual investment details, and verify transaction-specific requirements with qualified tax and legal professionals. Multifamily Schooled offers education, workshops, software, and mentorship to help apartment investors strengthen their knowledge and evaluate opportunities more systematically. These resources support investor preparation, not tax or legal advice or a promised investment outcome.
Ready to build your multifamily investing knowledge with structured guidance? Explore multifamily investing mentorship and take your next step with a clearer plan.
Frequently Asked Questions
Can you use a 1031 exchange to buy a multifamily property?
Yes, qualifying investment or business real property may be exchanged for other qualifying real property, including a multifamily property, subject to current Section 1031 rules. The fact that the replacement is an apartment building doesn’t by itself make the transaction eligible. The property’s use, ownership, exchange structure, and other transaction details matter. Before relying on tax deferral, have qualified tax and legal professionals review how the rules apply to your circumstances.
Can a DST qualify as replacement property in a 1031 exchange?
Some beneficial interests in Delaware Statutory Trusts may qualify as replacement property when the trust structure and exchange meet applicable requirements. That doesn’t mean every DST or investor situation qualifies, or that a DST works like direct ownership. DST investors generally have limited control over the underlying property and may face restrictions on liquidity and transfers. Review the specific offering documents and get transaction-specific tax guidance before deciding.
What are the deadlines for a 1031 exchange?
The commonly cited deadlines are 45 days after transferring the relinquished property to identify potential replacements and 180 days to acquire one. The periods run concurrently. For some fourth-quarter sales, the exchange period may be shortened by the tax return filing deadline unless an extension is filed. Counting rules and exceptions can affect the dates. Plan before the sale closes, and verify current IRS requirements for your transaction.
Do I need a qualified intermediary for a 1031 exchange?
A qualified intermediary generally facilitates a deferred exchange and holds the sale proceeds so the investor doesn’t take receipt of them during the exchange. Control and handling of the funds matter because constructive receipt can jeopardize the intended treatment. The process and requirements depend on current rules and transaction facts, so don’t treat this overview as legal advice. Confirm the intermediary’s role and required steps for your specific exchange before closing.
What is the difference between owning multifamily property directly and investing through a DST?
Direct ownership typically means more involvement in property selection, financing, operations, and asset-level decisions, although actual authority depends on agreements and partners. DST investors generally participate more passively, with limited control over daily operations. Both routes expose investors to property performance, while DST interests may have limited liquidity. Review the property, sponsor, debt, fees, and exit terms. Each offering is different, so don’t assume the structures have the same risks or outcomes.
Can I exchange one type of investment property for an apartment building?
In general, Section 1031 allows qualifying real property held for investment or productive use in a business to be exchanged for other qualifying real property of like kind. The properties don’t necessarily need to be identical, but not every property type, ownership arrangement, or transaction qualifies. The specific assets, their use, and current law matter. Have qualified tax and legal professionals assess your facts before treating an apartment building as an eligible replacement.
What happens if I miss a 1031 exchange deadline?
Missing a required identification or acquisition deadline can jeopardize the intended exchange treatment, but the precise tax consequences depend on the transaction and applicable rules. Don’t assume an exception or workaround applies. Deadlines, counting methods, exceptions, and any potential relief must be checked against current requirements and your documents. If a deadline is approaching or may have passed, promptly seek transaction-specific guidance from qualified tax and legal professionals rather than relying on a general article.



